Key takeaways
- One equation runs the fund: the slips plus the cash in the box equal the fund. IRS Publication 583 puts it the same way, and every check in the log comes back to it.
- Top up by the fund minus the cash you count, not the total of the slips. The two match only when the box is exactly right, which is what the IRS's own $50 example assumes. In the example below, the slips total $123.22 and the box is $0.50 short, so the check is $200.00 − $76.28 = $123.72.
- Under the usual fixed-fund method you book the expenses when you top up, in one entry by category, and the Petty Cash account stays at the fund. QuickBooks Online's method books each slip as it happens instead. Use one or the other: doing both counts the spending twice, and it's one way Petty Cash in the books stops matching the box.
- There's no general under-$75 receipt exception. That rule covers travel, gift and car expenses only. For any other cash payment without a receipt, the IRS asks for an adequate explanation written at the time.
- Cash paid to a person for work counts toward Form 1099-NEC: $2,000 or more in a year for 2026 payments. Get a Form W-9 before the cash leaves the box.
What is a petty cash log?
In short: The running record of a small, fixed amount of cash kept for little payments: one line for every payout, the cash left after it, and the count and top-up at month end.
In this guide's example, Ana Ruiz, the office manager at Maple Street Dental, keeps a locked cash box in her desk. The practice needs stamps, a parking meter fed, or a box of pens from the store down the road. The cash comes from the box, and a slip goes in. Some offices call these payouts "paid outs".
Petty cash covers the payments too small for a check or a card. The IRS describes the idea in Publication 583, its guide to starting a business and keeping records:
“A petty cash fund allows you to make small payments without having to write checks for small amounts. Each time you make a payment from this fund, you should make out a petty cash slip and attach it to your receipt as proof of payment.”
The log lists those slips in order. Its job is the check at the end: whatever has been paid out, the slips and the cash left in the box should add up to the fund.
The IRS's own example is a $50 fund, and it states the rule plainly: "The total of the unspent petty cash and the amounts on the petty cash slips should equal the fixed amount of the fund."
Maple Street Dental, October 31: slips + cash + shortage = the $200.00 fund
- Slips: $123.22
- Cash counted: $76.28
- Short: $0.50
Each column in the log has a job. Leave one out, and the month-end check gets harder:
| Column | Why it's there |
|---|---|
| Slip number (PC-001, PC-002...) | Ties the log line to the paper slip and shows if a slip is missing |
| Date | Puts the expense in the right month |
| What it was for, and paid to | The business reason, which matters most when there's no receipt |
| Category | The expense account, so the top-up entry can be written straight from the totals |
| Amount out | What left the box |
| Balance after | The cash that should be in the box at that moment, for a spot count any day |
| Receipt (yes or no) | Shows at a glance which slips need a written explanation |
| Taken by, approved by | Who had the cash, and who said yes. They're on the paper slip, and in the Excel Log and the CSV; the printed log leaves them to the slips |
The tool above is that log with the arithmetic done for you, and it opens on a sample month already filled in.
The rest of this guide follows that fund: Maple Street Dental's $200 front-office box in October 2026, kept by Ana, with the dentist, Nina Shah, approving the slips. The practice and the people are fictional; the rules are the IRS's and the textbooks'.
How do you set up a petty cash fund?
In short: Pick a fixed amount, give the box to one person, and fund it with a check or transfer for that amount. In the books it's a move from checking to Petty Cash, not an expense.
On October 1, Dr. Nina Shah, Maple Street Dental's dentist and owner, writes a $200 check to "Petty Cash". Ana cashes it, and the log starts at $200.00. Four decisions got the fund there:
- Choose the amount. No rule sets it. Size it to about a month of the small cash payments the business really makes, so you top up once a month and the expenses land in the right month. If it runs dry mid-month, raise it later; if cash sits unused, lower it. That sizing is our suggestion, not a requirement.
- Name one custodian. One person holds the key and hands out the cash, so every difference has an owner. Someone else approves the top-ups and records them in the books.
- Write the rules down: what petty cash can pay for, a per-purchase limit if you want one, and what it can't pay for. Wages always go through payroll. Two university policies we read cap each purchase at $100.
- Fund it. Write a check to "Petty Cash" or transfer the amount, cash it, and put the cash in a locked box with a stack of blank slips. The tool prints blank slips, four to a page.
| Account | Debit | Credit |
|---|---|---|
| Petty Cash | $200.00 | |
| Checking | $200.00 |
Nothing is spent yet, so there's no expense: cash has only moved from the bank account to the box. In QuickBooks Online, Intuit's help sets up a Petty Cash account with the detail type Cash on hand, funded with a check or a transfer.
Bookkeeper tip: Keep the fund small enough that losing all of it wouldn't hurt. The box is the one place in the business where money can leave without a bank record. So the fixed amount is also the most that can go missing between two counts, which is one reason to count every month.
How do you keep track of petty cash day to day?
In short: A slip for every payout, with the receipt attached, and a line in the log the same day. The running balance then tells you what should be in the box at any moment.
Here's Maple Street Dental's October. Each line is a slip in the box and a row in the log:
| Slip | Date | What it was for · paid to | Category | Receipt | Out | Balance |
|---|---|---|---|---|---|---|
| Oct 1 | Fund at the start | $200.00 | ||||
| PC-001 | Oct 2 | Printer paper and pens · Staples | Office supplies | Yes | $18.45 | $181.55 |
| PC-002 | Oct 6 | Stamps for patient statements · USPS | Postage and shipping | Yes | $12.60 | $168.95 |
| PC-003 | Oct 9 | Parking for the bank deposit · meter | Parking and tolls | No | $9.00 | $159.95 |
| PC-004 | Oct 14 | Window cleaning · Dan Reyes | Cleaning and maintenance | Yes | $60.00 | $99.95 |
| PC-005 | Oct 21 | Toner cartridge · Office Depot | Office supplies | Yes | $23.17 | $76.78 |
Every slip also names who took the cash and who approved it. Dr. Shah signs the slips, except the parking: Ana approved that one when Luis Ortega took the day's deposit to the bank.
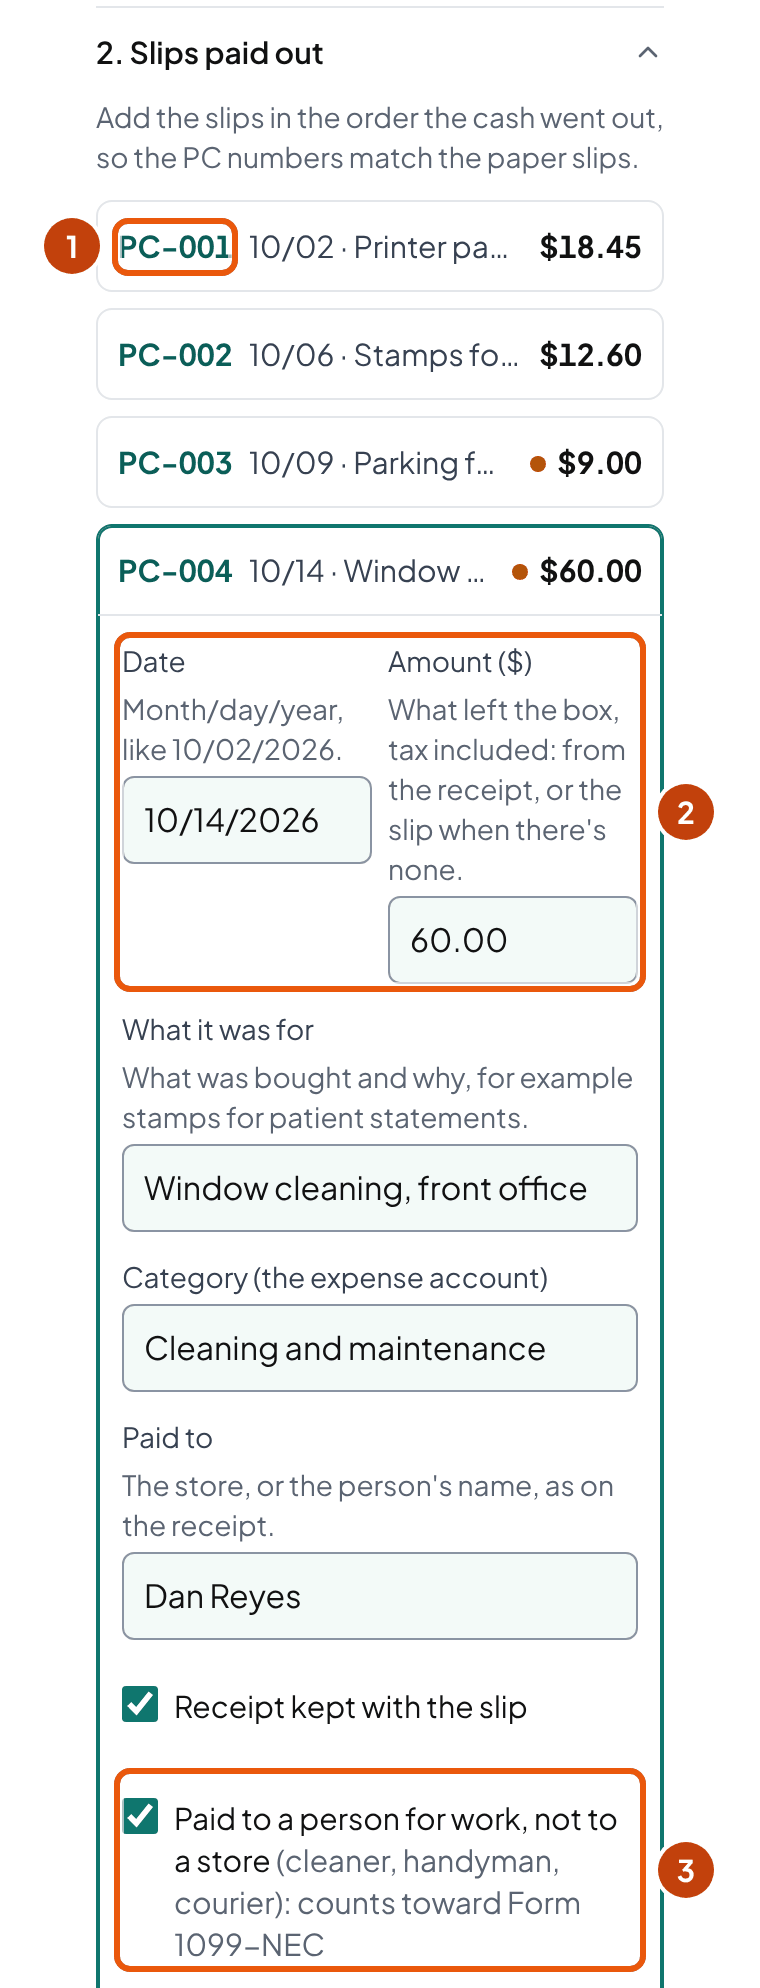
Three of those lines need more than a receipt. The parking meter gave no receipt, so the slip has to carry the explanation (below). Dan Reyes is a person paid for work, not a store, so his $60.00 counts toward a possible Form 1099-NEC (below).
The toner and the paper go to the same category, which is why the top-up entry has one line for Office supplies, $41.62.
Rules that keep the log honest
- Write the slip when the cash leaves the box, not at month end from memory. A record made at the time is worth more than one rebuilt later, and for a missing receipt the IRS asks for the explanation "at the time of payment".
- Never change an old line. If a slip was wrong, fix it with a new line or at the count, so the log still matches the paper in the box.
- One box, one purpose. Customer cash belongs in the register, not in petty cash. If one box holds both, count and record them separately: the customer cash is sales.
- Change comes back with the receipt. If Ana takes $20 for stamps that cost $12.60, the slip says $12.60 and the $7.40 goes back in the box the same day.
How do you reconcile and replenish petty cash?
In short: Count the cash first, then top up by the fund minus the cash you counted, not by the total of the slips. Any difference goes to Cash Over and Short. Once the box is topped up (replenished, in the textbooks), it holds the full fund again and the next month starts from there.
- Start$200.00The fund, in the box on October 1
- Slips$123.225 payouts leave $76.78 in the box
- Count$76.28Counted October 31: $0.50 short
- Check$123.72$200.00 − $76.28, written to “Petty Cash”
Back to $200.00: the next period starts from a full box.
- Count before you look at the log, with a second person watching. Write the total on the count sheet, and both of you sign it. Counting first keeps the count honest: you write what's there, not what should be.
- Add up the slips. Every slip in the box gets a line in the log, and every line has its slip. A slip with no line is a shortage waiting to be found; a line with no slip is a payout nobody can prove.
- Work out what should be in the box: the fund minus the slips.
- Compare. The cash counted minus what should be there is the difference: below zero the box is short, above zero it's over.
- Top up by the fund minus the cash counted. That brings the box back to exactly the fund, whatever the difference was.
| Fund | $200.00 |
| Slips: $18.45 + $12.60 + $9.00 + $60.00 + $23.17 | − $123.22 |
| Should be in the box | $76.78 |
| Cash counted by Ana and the dentist | $76.28 |
| Short: $76.78 − $76.28 | $0.50 |
| Top-up: $200.00 − $76.28 | $123.72 |
The top-up is $123.72: the $123.22 of slips plus the $0.50 shortage. Write the check for $123.72, not $123.22, or the box starts November $0.50 light.
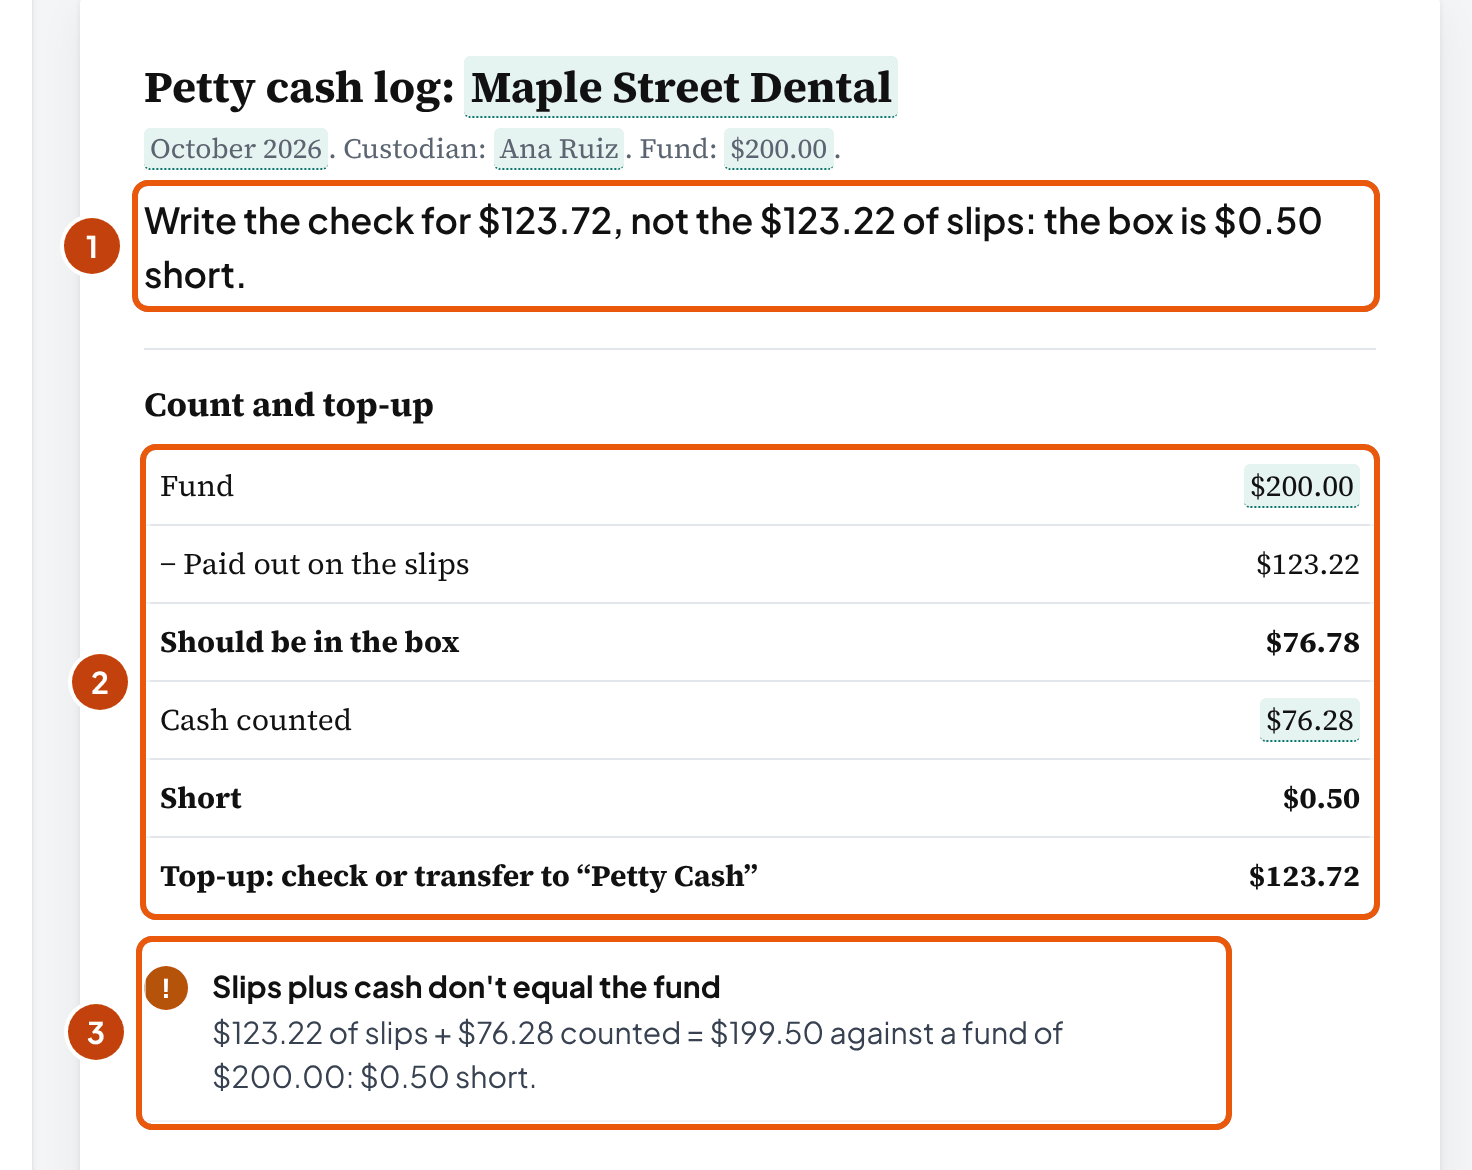
Why not top up by the total of the slips? That's right only when the box is neither over nor short, the case the IRS's example in Publication 583 describes. In that example, Henry refills his $50 fund with a check "for the total of the outstanding slips".
Xero's US petty cash guide says the same: request a check or transfer "for the exact amount spent".
OpenStax's textbook example handles the other case. Its $75 fund holds $45 of receipts and $25 of cash, and the top-up covers the receipts plus the $5 shortage. A top-up worked out as the fund minus the cash counted can't drift from one month to the next, because it's defined by where the box has to end up.
Over or short: Cash Over and Short
Small differences have ordinary causes: change given wrong at a store, a coin dropped, a slip rounded. Book them to an account called Cash Over and Short (some charts call it Cash Short and Over).
A shortage is a debit, like an expense; an overage is a credit, like income. OpenStax's accounting textbook uses the same account in its petty cash example, a $75 fund that comes up $5 short.
Before you book it, count again and look for a slip that never made it into the log. A slip that was paid but never logged explains a shortage to the cent, and it belongs to its real expense account.
Don't book an unexplained shortage to owner's draws because the business is small. That's right only when the owner took the cash, which is a question to ask, not a default.
Bookkeeper tip: Watch the pattern, not the size. A $0.50 shortage once a year means nothing. The same few dollars missing every month, always under the same custodian, is a reason to count with a second person and change who has the key.
What are the journal entries for petty cash?
In short: Under the usual fixed-fund method, one entry when you top up: debit each expense category and any shortage, credit checking. QuickBooks Online's method books each slip as it happens and makes the top-up a transfer.
The textbook method (fixed or imprest fund)
The payouts get no entry when they happen. At the top-up, you add up the slips by category and record them in one entry, and the check refills the box.
The Petty Cash account itself doesn't move. OpenStax puts it this way: the balance "will never change and will remain on the balance sheet at $75, unless management elects to change the petty cash balance." AccountingCoach says the same: "There is no entry to the Petty Cash account when merely replenishing the petty cash."
| Account | Debit | Credit |
|---|---|---|
| Office supplies ($18.45 + $23.17) | $41.62 | |
| Postage and shipping | $12.60 | |
| Parking and tolls | $9.00 | |
| Cleaning and maintenance | $60.00 | |
| Cash Over and Short | $0.50 | |
| Checking | $123.72 |
Debits $123.72, credit $123.72. This is the entry the IRS example describes: when the fund is restored, the slips are summarized and entered "in the proper columns" of the disbursements journal.
Can you lump all the receipts into one entry? Under this method, yes: one entry each time you top up, with one line per category. Maple Street Dental's five slips become four expense lines and the $0.50 shortage.
Petty Cash stays at $200.00. You can prove it on the balance sheet reconciliation, where the account's balance is matched to the cash counted plus the slips not yet booked.
Changing the size of the fund is the only time Petty Cash moves. Say Maple Street Dental raises its fund from $200 to $250 at this top-up. The check is then $250.00 − $76.28 = $173.72, and the extra $50.00 goes to Petty Cash:
| Account | Debit | Credit |
|---|---|---|
| Office supplies | $41.62 | |
| Postage and shipping | $12.60 | |
| Parking and tolls | $9.00 | |
| Cleaning and maintenance | $60.00 | |
| Cash Over and Short | $0.50 | |
| Petty Cash | $50.00 | |
| Checking | $173.72 |
The QuickBooks Online method
Intuit's help article for QuickBooks Online sets up Petty Cash as its own cash account. It says to "record taking cash from petty cash as an expense with petty cash as the payment account."
So each slip becomes its own expense the day it's paid. The Petty Cash balance falls through the month, and the top-up is a transfer from checking that brings it back up. The article also says the slips and the cash left "should add up to the amount you deposited in the box", the same check as the IRS's.
After the transfer, Petty Cash reads $200.00 again: $200.00 − $123.22 of slips − $0.50 short + $123.72 = $200.00. That's the figure the balance sheet reconciliation proves.
| Textbook method | QuickBooks Online method | |
|---|---|---|
| When a slip is paid | No entry | An expense, paid from Petty Cash |
| Petty Cash during the month | Stays at $200.00 | Falls to $76.78 |
| Shortage at the count | A line in the top-up entry | An expense paid from Petty Cash, $0.50 |
| The top-up | Expenses by category, credit Checking $123.72 | Transfer, Checking to Petty Cash, $123.72 |
| Good for | Few slips, books kept monthly | Books kept in QuickBooks during the month |
Pick one method and stay with it. The mistake that matters here is mixing them: recording each slip as an expense during the month, then booking the top-up check to expenses too. The same $123.22 of spending is then in the books twice. In the tool, choose the method your books already use, and the entries follow it.
For the entries around this one (the deposit, the expenses paid by check, the month-end accruals), see more entries in the journal entry builder.
Why doesn't Petty Cash in the books match the box?
In the Reddit posts we read, one petty cash problem kept coming up: a Petty Cash account in the books that never matched the cash in the box.
The test is the one the balance sheet reconciliation uses: Petty Cash in the books equals the cash counted plus the slips not yet booked.
Say Maple Street Dental's books show Petty Cash at $250.00 on October 31, before the top-up, under the textbook method. The box holds $76.28, and the slips not yet booked total $123.22. That accounts for $199.50, a difference of $50.50.
Of that, $0.50 is the shortage the count found, which the top-up entry books to Cash Over and Short. The other $50.00 is left to explain: something the books recorded and the box never saw. List what the books did that the box didn't, and check these first:
- The spending booked twice. Under the QuickBooks Online method, each slip went in as an expense paid from Petty Cash, and then the top-up check went to expenses too, not to Petty Cash. The books show Petty Cash lower than the box, and the spending twice.
- The funding check booked as an expense. Under the QuickBooks Online method, Petty Cash never received the fund, so once slips are paid from it the balance goes below zero. A negative balance is one sign of this.
- Slips never posted. Under the QuickBooks Online method, Petty Cash stays higher than the box until the slips are booked.
- A fund change booked but never made. A check to make the fund bigger, recorded to Petty Cash but never cashed into the box, leaves the books higher by that amount.
- Cash the owner took. The box is lower than the books, with no slip. Ask; don't assume.
In Maple Street Dental's case, the $50.00 is the fourth: a fund raised to $250 in the books but never cashed.
Petty Cash in the books: $250.00
What the box and the slips account for: $199.50
- Cash counted: $76.28
- Slips not yet booked: $123.22
- Shortage at the count: $0.50
- Left to explain: $50.00
If the check for the extra $50.00 was never written or never cleared the bank (the month's bank reconciliation shows which), the fix reverses the entry that raised the fund: debit Checking $50.00, credit Petty Cash $50.00. If it did clear, the $50.00 left the bank and never reached the box, which is a question for whoever cashed it.
What the tool shows
Petty Cash in the books doesn't match the box $250.00 in the books − ($76.28 counted + $123.22 of slips not yet booked) = $50.50; $0.50 is the shortage the count found, and $50.00 is left to explain.
In the tool: type the books balance in "Petty Cash in the books" (step 4, How your books record it). Under the QuickBooks Online method the tool counts no slip as unbooked, because each one was booked when it was paid. Open the tool ↑
Fix the cause with an entry dated in the current month, with a note saying what it corrects. Don't change an old opening balance to clear the difference: it rewrites months already closed and hides the cause.
A remainder you can't explain is a question for the client, as in a box with no log.
What if there's no receipt?
In short: Write the explanation on the slip when you pay: what was bought, from whom, and why. There's no general rule that payments under $75 need no receipt.
IRS Publication 583 covers the case in one line: "If you cannot get a receipt for a cash payment, you should make an adequate explanation in your records at the time of payment." A parking meter, a tip to a delivery driver, a bus fare: each still gets a slip, signed by whoever took the cash.
A slip with no receipt
Oct 9, 2026. $9.00, city parking meter on Main St., 1 hour, while Luis Ortega took the day's deposit to First Community Bank. No receipt from the meter. Signed: Luis Ortega. Approved: Ana Ruiz.
In the tool: untick "Receipt kept" on the slip; the log flags it and the Excel file counts slips without receipts on the Month end tab. Open the tool ↑
Where does the "under $75" rule come from? From the IRS rules for travel, gift and car expenses. Publication 463 says documentary evidence isn't needed if "Your expense, other than lodging, is less than $75". The regulation behind it, 26 CFR 1.274-5, applies only to those expenses.
So it isn't a rule for stamps or toner. Even where it applies, the record of what, when, where and why is still needed.
Bookkeeper tip: Publication 583 also notes that "Proof of payment of an amount, by itself, does not establish you are entitled to a tax deduction." The slip shows the cash left; the description shows it was for the business. Keep both, and keep them as long as the return they support can be examined.
Can you pay a person from petty cash?
In short: Yes, but cash paid to a contractor counts toward Form 1099-NEC: $2,000 or more in a year for 2026 payments. Get a Form W-9 first. Wages never come out of petty cash.
Dan Reyes cleans Maple Street Dental's windows and gets $60.00 from the box each month. He isn't an employee or a corporation, so his cash payments add up toward Form 1099-NEC. The IRS instructions list four conditions:
- the payee isn't your employee
- the payment is for services in the course of your business
- it's made to an individual, partnership or estate (or in some cases a corporation)
- the total is "at least $2,000 during the year."
Nothing in them excludes cash; that's our reading. Payments by card are reported by the card processor on Form 1099-K instead.
- The threshold changed. For tax years beginning after 2025 it's $2,000, up from $600, and it may be adjusted for inflation from 2027. Publication 583 still says $600; the 1099 instructions are newer.
- Ask for a Form W-9 before you pay. The IRS form exists so the payer can get the payee's taxpayer identification number. Ask while the person is there, because in January the form has to be chased.
- Without the number, backup withholding can apply. A payee who never gives a taxpayer identification number can put the business under the backup withholding rules. That means holding back 24% of the payment, which is hard to do with cash from a box.
- Form 1099-NEC goes to the payee and the IRS by January 31. The form's instructions say section 6071(c) "requires you to file Form 1099-NEC on or before January 31", on paper or electronically. A due date that lands on a weekend or holiday moves to the next business day.
- For 2026 payments, that's Monday, February 1, 2027. By our count of the calendar, January 31, 2027 is a Sunday. Check the IRS's own calendar when it's out.
- Add petty cash to everything else. $60 a month from the box is $720 a year, and if the same person is also paid by check, the two add up. The accounts payable template tracks 1099 payees the same way for the bills paid by check, so you can add the two totals at year end.
Tick "Paid to a person for work" on the slip, and the tool totals each person's payments for the period and flags them. Some organizations avoid the question entirely: the University of Houston System's petty cash policy, for example, rules out payments to individuals for personal services.
Cash advances to employees
Cash handed out before a purchase, for example $100 for supplies on a trip, isn't an expense yet. Keep a signed IOU slip in the box until the receipts and change come back.
How does it stay out of the employee's wages? The federal rules for accountable plans set a reasonable-time safe harbor in 26 CFR 1.62-2. The advance is made within 30 days of the expense, the receipts come in within 60 days after it, and any unspent cash comes back within 120 days.
When the owner pays from their own pocket
Say Dr. Shah buys office supplies with her own cash and drops the receipt in the box. That isn't a petty cash payout, because no cash left the box. Logged as a slip, it makes the box come out over at the count.
Keep it out of the log. Record it as money the business owes her, repaid by check, or as her contribution to the business. Which one is the owner's call, so ask and keep the answer in writing. For cash going the other way, from the business to the owner, see how owner draws are taxed.
Which petty cash controls matter in a small office?
In short: Three: one person holds the cash, someone else records and approves, and someone counts without warning now and then. A per-purchase limit helps; a big fund doesn't.
Small organizations stand out in the fraud cases examiners report. The ACFE's 2026 Report to the Nations is a study of 2,402 occupational fraud cases investigated by its members. In it, organizations with fewer than 100 employees had the highest median loss of any size group, $126,000.
In those smaller organizations, theft of cash on hand appeared in 13% of cases, against 8% for larger ones. Expense reimbursement schemes appeared in 19%, against 10%. Across all sizes, cash on hand schemes ran a median of 9 months before they were caught.
| Control | What it looks like in a small office | Where it comes from |
|---|---|---|
| Separate custody, recording and approval | Ana holds the box; the bookkeeper records the top-up; the dentist signs the check | GAO Green Book, segregation of duties: separate "authorizing transactions, processing and recording them, reviewing the transactions, and handling any related assets" |
| Physical control | A locked box, one key, kept out of sight | GAO Green Book: limited access to "assets such as cash" and periodic counts compared with the records |
| Surprise counts | The owner counts the box on a random day against the log's balance | University of Houston System policy: funds "are subject to surprise cash counts"; ACFE 2026: median loss $74,000 where surprise audits were in place, $149,000 where they weren't (an association, not proof) |
| Per-purchase limit | Anything over $100 goes on the business card | University of Houston System and UNC Charlotte policies: $100 per transaction |
| Monthly top-up | Top up at month end even if the box isn't empty | OpenStax: monthly reimbursement "ensures that the expenses are recognized within the proper accounting period" |
The university policies are one institution's rules each, not law. They show what a written policy covers: the limit, who the custodian is, surprise counts, receipts, and what petty cash can't pay for.
UNC Charlotte's, for example, rules out using it to pay wages for students or temporary employees. If a client has no written policy, those five points are a starting outline.
What if a client's petty cash has no log?
In short: Count the box today, collect whatever receipts are in it, and start the log from today's count. Don't try to rebuild months nobody recorded.
- Count the cash with the client present and write the date and total down. That is the only number you know for sure.
- Match the receipts in the box to categories. Record the business purchases as expenses of the months they belong to. If those months are closed or the return is filed, record them in the current month.
- Compare with the books. Petty Cash in the ledger should equal the cash counted plus the receipts not yet booked (what to check when it doesn't). What's left is unexplained, so ask the client whether they took cash for themselves (owner's draws). A small remainder can go to Cash Over and Short. A large one, or one that spans years, is a question for the client and their tax preparer, not an expense to book quietly.
- Reset the fund. Pick the fixed amount going forward, top the box up to it, and start the log with today's date and that amount. From here the equation holds again.
Bookkeeper tip: Put the starting count and the agreed fund amount in writing, signed by the client. When the first month-end comes, the difference you find is the client's first month, not the last three years.
How do you make a petty cash log in Excel?
In short: One input cell for the fund, a row per slip, and three formulas: the running balance, the total, and the top-up. Or download ours, which has them already.
The formulas below are the file's own. The cell addresses are from the file as downloaded with up to 25 slips; the total row moves down with more.
| Cell | Formula | What it does |
|---|---|---|
| C7 | 200 | The fund (an input, in yellow) |
| H10, copied down | =IF(G10="","",ROUND($C$7-SUM($G$10:G10),2)) | Balance after each slip: the fund minus everything paid out so far, rounded to the cent, blank until there's an amount |
| G51 | =ROUND(SUM(G10:G49),2) | Total paid out |
| Month end B7 | =ROUND(B5-B6,2) | Cash that should be in the box: fund minus total paid out |
| Month end B9 | =IF(B8="","",ROUND(B8-B7,2)) | Over (+) or short (−): counted minus what should be there, blank until you count |
| Month end B11 | =IF(B8="",ROUND(B10-B7,2),ROUND(B10-B8,2)) | Top-up: the fund after the top-up minus the cash counted (minus what should be there until you count) |
| By category B5 | =ROUND(SUMIF('Log'!$D$10:$D$49,A5,'Log'!$G$10:$G$49),2) | Total for one category, the line for the top-up entry |
Why work the balance out from the fund each time, rather than from the row above? Because then a blank row or a deleted line can't break every balance below it.
The download also rounds each total to the cent. It has drop-down lists for the category and the yes-or-no columns, a bill-and-coin count, and the journal entry built from the totals. The Month end tab also compares Petty Cash in the books with the box when you type the books balance. So the file works as next month's log too. It's a standard .xlsx file, so Google Sheets and LibreOffice open it as well.
Rather keep the log on paper? The tool prints a blank log with 25 lines and the month-end count. For a log you can edit in Word, Download Word in the Save & share options menu gives the same log, count and entry as a .docx.
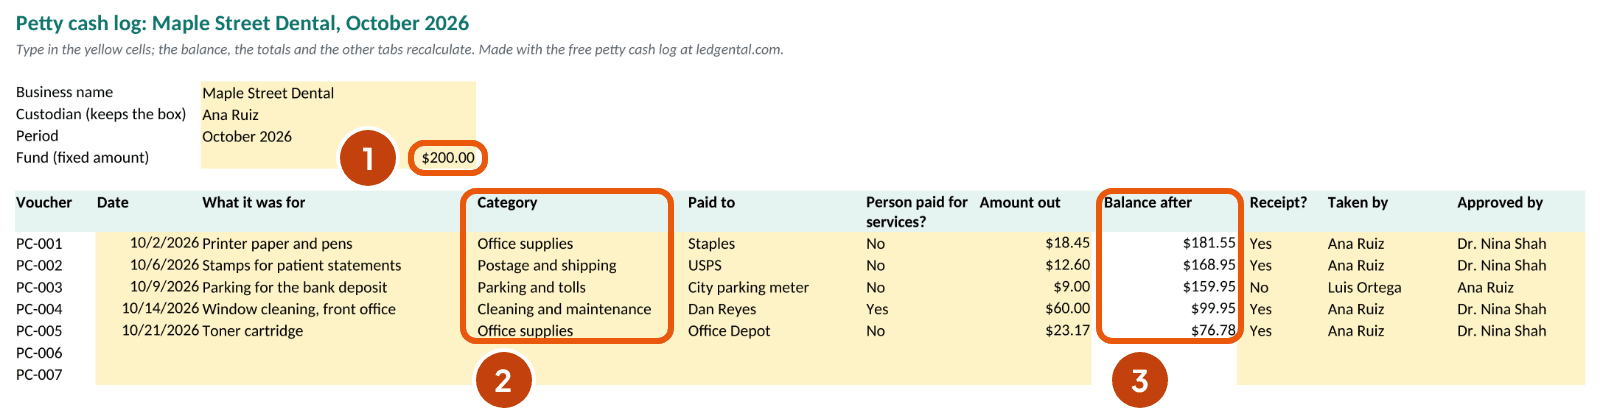
A "petty cash book" is the same record with one column per category, often called an analytical petty cash book. Totaling each column gives the debits for the top-up entry. The By category tab does the same job without making the log wide.
Petty cash slip, form, voucher, sheet, book or report: which is which?
In short: They're parts of one record, and no rule defines the names. On this page, the slip (a voucher or form on template sites) is the proof of one payment. The log or sheet lists the slips, the book adds a column per category, and the report is the month-end summary.
A dentist may ask for "the petty cash form", a bookkeeper for "the petty cash report", and a template site may offer a "petty cash book". Publication 583 uses one of these words, slip. The rest come from template sites and software help pages.
Here's how this page uses each name, and where it lives in the tool:
| Name | What it is | In the tool |
|---|---|---|
| Petty cash slip, voucher, or form | The proof of one payment: date, amount, what it was for, who took the cash, who approved it, and the receipt stapled to it. Publication 583 calls it a slip: "make out a petty cash slip and attach it to your receipt as proof of payment". | Print blank petty cash slips, four to a page, in the Save & share options menu |
| Petty cash log, sheet, or register | The list of slips in order, with the running balance after each one | The log on screen, the Excel Log tab, the CSV download, and Print a blank log |
| Petty cash book (columnar or analytical) | The same log with one column per expense category, so each column's total is one line of the top-up entry | The Excel By category tab does the same with a SUMIF per category, so the log stays narrow |
| Petty cash count sheet or reconciliation form | The month-end comparison: the cash counted, bill by bill, against what the log says is left | Step 3 in the tool (The count and top-up), the Excel Cash count and Month end tabs, and the count lines at the foot of the printed blank log |
| Petty cash report or summary | What the owner or the bookkeeper sees at month end: paid out by category, over or short, the top-up to write, and the journal entry | The printed log (Print the log or save as PDF) and the Word download |
| Petty cash request or reimbursement form | A request for cash before a purchase (an advance), or the request to the owner to refill the box | The top-up line is the refill request; an advance is a signed IOU slip until the receipt comes back (below) |
Common petty cash mistakes
In short: Most of them come from losing sight of the one equation: slips plus cash equal the fund.
| Risky | Safer |
|---|---|
| Topping up by the total of the slips | Topping up by the fund minus the cash counted, so a shortage doesn't carry into next month |
| Booking each slip as an expense and then the top-up check to expenses too | One method: the top-up entry by category, or each slip as an expense with the top-up as a transfer |
| Counting the box after reading the log's balance | Counting first, with a second person, and comparing after |
| Booking an unexplained shortage to owner's draws by default | Cash Over and Short, unless the owner says they took it |
| Paying a cleaner in cash all year with no W-9 | A W-9 before the first payment, and the cash added to the year's Form 1099-NEC total |
| A box that also holds customer payments, counted as one | Customer cash in the register, or counted and recorded separately as sales |
| Topping up only when the box is empty | Topping up at month end too, so the expenses are in the right month |
| Editing last week's line to make the balance work | A new line or an over or short at the count, with a note |
| Changing an old opening balance so Petty Cash in the books matches the box | An entry dated this month that fixes the cause, with a note saying what it corrects |
If more than one of these sounds familiar, start at the count. Count the box today, enter the slips you have in the tool, and let the difference tell you how far off the records are.
What goes in each field?
In short: Only the fund amount is required, and a slip needs an amount to count. The tables list every input, what to enter, where the number comes from, and the range the tool accepts. A value outside the range is kept as typed, and the result says which value it uses until you fix it.
1. The fund and who keeps it
| Field | What to enter | Where to find it | Range and example |
|---|---|---|---|
| Fund amount | The fixed amount the box holds when it's full, the same figure as the Petty Cash account in the books | The check or transfer that created the fund, or the Petty Cash balance on the balance sheet | $0.01 to $100,000; example $200 |
| Custodian | The one person who keeps the box | Your petty cash policy; if there's none, whoever holds the key today | Example: Ana Ruiz |
| Business name | The name at the top of the log and the Excel file | Any name the client goes by; it only labels the file | Example: Maple Street Dental |
| Period | The month the log covers | The month you're counting; one month per log keeps each top-up in its month | Example: October 2026 |
2. Slips paid out
| Field | What to enter | Where to find it | Range and example |
|---|---|---|---|
| Date | The day the cash left the box | The slip; today is filled in for a new slip | Month/day/year, like 10/02/2026 |
| Amount | What left the box, in dollars and cents, tax included | The receipt, or the slip when there's no receipt | $0 to $100,000, at most two decimals; example $18.45 |
| What it was for | What was bought and why | The slip's description; it matters most with no receipt | Example: stamps for patient statements |
| Category | The expense account the payout posts to | Your chart of accounts; the list has nine common ones and Other | One of the list; a slip with none is totaled on its own line until you pick one |
| Paid to | The store, or the person's name | The receipt | Example: USPS, or Dan Reyes |
| Receipt kept with the slip | Ticked when the receipt is stapled to the slip | The slip | Untick it and the log flags the slip for a written explanation |
| Paid to a person for work | Ticked when the cash went to a person for services, not to a store | Ask: an individual, not a company, doing work for the business | Totals each person's payments toward Form 1099-NEC |
| Cash taken by | Who took the cash out of the box | The signature on the slip | Example: Luis Ortega |
| Approved by | Who said yes to the payout | The slip; leave it blank when nobody did | Optional; example: Dr. Nina Shah |
3. The count and top-up
| Field | What to enter | Where to find it | Range and example |
|---|---|---|---|
| How you'll enter the count | One total, or bills and coins | Bills and coins is the count sheet; it adds up for you and goes to the Excel Cash count tab | One of the two |
| Cash counted in the box | The bills and coins in the box right now, not what the log says | Count with a second person watching, before you look at the log | $0 to $100,000; example $76.28 |
| Bills and coins | How many of each, from $100 bills to pennies | The count | Whole numbers, up to 100,000 of each |
| Fund amount after the top-up (optional) | A new fund size, only if you're changing it | Your decision: bigger if the box runs dry mid-month, smaller if cash sits unused | Empty, or $0.01 to $100,000; empty keeps the fund as it is |
4. How your books record it (optional checks)
| Field | What to enter | Where to find it | Range and example |
|---|---|---|---|
| How your books record petty cash | Textbook method or QuickBooks Online method | How your books already treat the slips: no entry until the top-up, or an expense per slip (the entries) | One of the two |
| Petty Cash in the books (optional) | The Petty Cash balance in the books on the count date, before the top-up is booked | The balance sheet, or the Petty Cash register in QuickBooks | Empty, or −$10,000,000 to $10,000,000; it can be below zero. Example: $250.00 (books vs box) |
| Per-purchase limit (optional) | A cap on any one payout, set by the business | Your policy; two university policies we read use $100 | Empty, or $0.01 to $100,000 |
Frequently asked questions
What is a petty cash log?
A petty cash log is the running record of a small cash fund. Each payout gets one line: the date, what it was for, who was paid, the amount, and the cash left. At month end the log adds the count and the top-up. With a $200 fund and $123.22 of slips, the log says $76.78 should be in the box, which is what the count is checked against.
How do I create a petty cash log in Excel?
Put the fund amount in one cell and give the log these columns: slip number, date, what it was for, category, paid to, whether the payee is a person paid for services, amount out, balance after, receipt yes or no, taken by, and approved by. The balance formula is the fund minus the sum of the amounts so far, for example =$C$7-SUM($G$10:G10), copied down. Add a total, a cell for the cash counted, and a top-up cell that is the fund minus the cash counted. The free download on this page has those formulas, plus a category summary, a bill-and-coin count and the journal entry.
How do you do a petty cash log?
That's how you keep track of petty cash: give one person the box, write a slip for every payout with the receipt stapled to it, and record each slip in the log the same day. At the end of each month, or whenever the box runs low, count the cash, check that the slips plus the cash equal the fund, and write a check or transfer for the fund minus the cash counted. IRS Publication 583 describes the same routine: the unspent cash plus the slips should equal the fixed amount of the fund.
How can I create a petty cash book in Excel?
A petty cash book is the same log with one column per expense category (an analytical petty cash book), so each payout's amount goes in its category's column as well as the total column. Totaling each column at month end gives the debits for the top-up entry. The download on this page does the same with a By category tab that adds up the log with SUMIF, so you keep one amount column and still get the totals by account.
How much money should be in a petty cash fund?
No rule sets it. A workable size covers about a month of the small cash payments the business actually makes, so the box is topped up once a month and the books get the expenses in the right month. IRS Publication 583 uses a $50 fund in its example; two university policies we read cap each purchase at $100. If the box runs dry before month end, raise the fund; if cash sits unused, lower it.
How do you make a petty cash report?
No rule defines the term. On this page a petty cash report is the month-end summary: the fund, the total paid out by category, the cash counted, the over or short, the top-up to write, and the journal entry. Make it at month end, and also whenever the cash runs low. OpenStax's accounting textbook says a monthly top-up puts the expenses in the right accounting period. The tool on this page prints that report from the slips you enter, or downloads it as Word or Excel.
What form shows proof of a petty cash payment?
The petty cash slip. That's the IRS's word in Publication 583; template sites call the same thing a petty cash voucher or a petty cash form. It records the date, the amount, what it was for, who took the cash and who approved it, with the receipt attached. IRS Publication 583 says to make out a petty cash slip for each payment from the fund and attach it to the receipt as proof of payment. The tool prints blank slips, four to a page.
What do you do when petty cash is short?
Count again with a second person, and look for a slip that wasn't logged. Then record what's left in Cash Over and Short, an account that works as an expense when the box is short and as income when it's over. The top-up is the fund minus the cash counted, so it covers the shortage too: with $76.78 expected and $76.28 counted, the top-up is $123.72, not the $123.22 of slips. Book it to owner's draws only if the owner actually took the cash.
Why doesn't petty cash in QuickBooks match the box?
Because the books recorded something the box never saw, or the other way round. Petty Cash in the books should equal the cash counted plus the slips not yet booked: under the usual fixed-fund method that's every slip until the top-up, and under QuickBooks Online's method it's none, because each slip is booked when it's paid. With $250.00 in the books, $76.28 in the box and $123.22 of slips, $50.50 is off: $0.50 is the count's shortage and $50.00 is left to explain. Check for a top-up booked to expenses on top of the slips, a funding check booked as an expense, slips never posted, a fund increase booked but never cashed, and cash the owner took. Fix the cause with an entry dated this month, not by changing an old opening balance. The tool on this page runs the same check when you type the books balance.
Is petty cash an asset?
Yes. Petty Cash is a current asset in the cash group on the balance sheet. Under the usual fixed-fund method it stays at the fund amount, such as $200, because the payouts are recorded as expenses when the fund is topped up, and the account changes only when the fund itself is made bigger or smaller.
Do you need a receipt for petty cash under $75?
There's no general under-$75 exception. The $75 rule is in the IRS rules for travel, gift and car expenses (Publication 463 and the regulation behind it). For other cash payments, IRS Publication 583 says that if you can't get a receipt, make an adequate explanation in your records at the time of payment. Write on the slip what was bought, from whom, and why.
Can you pay a contractor from petty cash?
You can, but it counts toward Form 1099-NEC like any other payment for services. For payments in 2026 a business files Form 1099-NEC for a non-employee it paid at least $2,000 for services during the year, early in the following year. Ask for a Form W-9 before you pay. Some organizations rule services out of petty cash altogether, as the University of Houston System's policy does, and wages always go through payroll.
What's the difference between petty cash and a cash drawer?
Petty cash is for paying small business expenses; a cash drawer or change fund holds the cash customers pay in. If a business keeps them in one box, count and record them separately: the customer cash is sales, and only the payouts belong in the petty cash log.
How we built this page
Ledgental Team wrote this guide and built the log. Ledgental also makes a bookkeeping app that's free during its beta; this tool doesn't connect to it. Everything you type stays in your browser.
What the numbers rest on
- The arithmetic starts from the IRS's fixed-fund equation: the slips plus the cash equal the fund, so what should be in the box is the fund minus the slips. The top-up is the fund minus the cash counted, which is the slip total adjusted for any over or short, as in OpenStax's example. Amounts are added in cents and rounded half away from zero, the way Excel's ROUND does. The engine is checked by 45 known-answer tests worked out by hand: the running example, an overage, a fund made bigger and smaller, a bill-and-coin count, a slip with no account chosen, a payout over the fund, the books against the box (both methods, a balance below zero), inputs that aren't valid, when the result adds a sentence above the top-up and when it doesn't, and the CSV. 6 more tests hold the Excel file's cell addresses and formulas to what this guide says.
- The books against the box uses the balance sheet reconciliation's test: Petty Cash in the books equals the cash counted plus the slips not yet booked. Under the textbook method no slip is booked until the top-up (OpenStax: the balance stays at the fund); under the QuickBooks Online method each slip is booked when it's paid (Intuit's help). The causes it lists are the ones in this guide's section, and the correcting entry names no account until you know the cause.
- The journal entries follow OpenStax's petty cash chapter and AccountingCoach for the textbook method, and Intuit's QuickBooks Online help for the register method. The tool checks that every entry balances.
- The tax points (no receipt, the $75 rule, Form 1099-NEC at $2,000, Form W-9, accountable-plan time limits) come from IRS publications, the 1099 instructions and the regulations, quoted in the text and read on October 4, 2026.
- Not covered: splitting sales tax out of purchases (enter what was paid), several funds in one log, foreign currency, cash registers and change funds, and payroll. Maple Street Dental and everyone in it are fictional.
What changed
- October 12, 2026: the guide is rewritten in shorter sentences and paragraphs, with the same figures and examples. It adds why Petty Cash in the books may not match the box, with the causes to check and the Maple Street Dental numbers. It also adds whether the receipts can go in one entry and what to do when the owner pays from their own pocket. The reference sections (the names and the field details) moved after the how-to.
- October 12, 2026, the tool: an optional Petty Cash in the books field compares the books with the box, shows what's left to explain and the correcting entry, and the Excel Month end tab does the same. The result now says which value it uses when the cash counted, the new fund size, the limit or the books balance isn't a valid amount, instead of using the old value without saying so. "Today unless you change it" shows only on a slip just added. The Form 1099-NEC note gives the weekend rule: February 1, 2027 for 2026 payments, by our count.
- October 11, 2026: added an "Approved by" field on each slip (in the CSV and the Excel Log too), a Word download of the log, the "Field details" section, and the section on what a petty cash slip, form, voucher, sheet, book and report each are; the slips figure recaptioned and the screenshots retaken.
- October 4, 2026: first published: the log with running balance, bill-and-coin count, over or short, top-up, both journal entry methods, flags for missing receipts, people paid for work and payouts over a limit; an Excel file with formulas, drop-downs and the entry; CSV; printable blank slips; and the guide.
Cite this page
Copy one of these lines to credit the page. To link to one section, use the link icon beside its heading.
- Plain line
- Ledgental, Petty Cash Log Template, updated October 2026, https://ledgental.com/tools/petty-cash-log-template
- APA
- Ledgental. (2026, October). Petty Cash Log Template. https://ledgental.com/tools/petty-cash-log-template
- Chicago
- Ledgental. “Petty Cash Log Template.” Last modified October 2026. https://ledgental.com/tools/petty-cash-log-template.
Reusing this page: the guide's text, tables, and screenshots are licensed under CC BY 4.0. Credit "Ledgental" with a link to this page. Quotations from the IRS and GAO are public domain, and quotations from other sources stay under their owners' terms.
Sources
- Publication 583, Starting a Business and Keeping Records (petty cash fund, Henry's $50 example, records without receipts), Internal Revenue Service
- Publication 463 (2025), Travel, Gift, and Car Expenses (the $75 documentary evidence exception), Internal Revenue Service
- Instructions for Forms 1099-MISC and 1099-NEC (12/2026): $2,000 threshold and the January 31 filing date, Internal Revenue Service
- About Form W-9, Request for Taxpayer Identification Number and Certification, Internal Revenue Service
- 26 CFR 1.274-5, Substantiation requirements, Cornell LII copy
- 26 CFR 1.62-2, Reimbursements and other expense allowance arrangements, Cornell LII copy
- Standards for Internal Control in the Federal Government (Green Book), GAO-14-704G, U.S. Government Accountability Office
- Principles of Accounting, Volume 1, 8.4: Petty Cash Fund and Petty Cash Journal Entries, OpenStax, Rice University (CC BY-NC-SA 4.0)
- What does it mean to replenish the petty cash fund?, AccountingCoach
- How is the account Cash Short and Over used?, AccountingCoach
- Set up and use petty cash in QuickBooks Online, Intuit
- Occupational Fraud 2026: A Report to the Nations, Association of Certified Fraud Examiners
- SAM 03.A.07, Petty Cash Funds (revised September 17, 2025), University of Houston System
- University Policy 602.3, Petty Cash Fund and Change Fund Policy, UNC Charlotte
General information, not tax or accounting advice. IRS rules and the other sources were read on October 4, 2026, and they change; check the current publication before relying on a figure. Maple Street Dental and the people in its example are fictional. This page isn't affiliated with the IRS, Intuit or any university.