Key takeaways
- A reconciliation compares each account's balance in the books with a document from somewhere else for the same date. It lists the items that explain the difference and shows what's still not explained.
- Explained isn't reconciled. A bank fee you found but never recorded explains the difference, but the books stay wrong until you post the entry. The template counts those accounts separately.
- Prove each account with the strongest document you can get. A bank, lender, card or payroll provider statement beats a report from the client's own software, which only shows the ledger agrees with itself.
- Age every item. The university policies we checked draw the line at 90 days. Texas A&M sends older items to a supervisor, and Baylor wants a written plan for anything over $10,000 and 60 days old.
- Some balances tie to IRS forms: quarterly 941s to the W-3, and a mortgage's principal to Form 1098 box 2, which only real-property loans to individuals get.
What is a balance sheet account reconciliation?
In short: Proof that each balance sheet account is right at a date. You compare the balance in the books with the same balance from another source, then list and explain every difference.
Baylor University's month-end policy puts it in one line: a reconciliation is a "comparison of a balance sheet account balance to a sub-ledger, source system or third-party source document." Texas A&M's says what it's for: it "detects errors, omissions, timing differences, or mis-postings."
Why the balance sheet? Income and expense accounts start over each year. A balance sheet account carries every past mistake forward until someone finds it, so these are the accounts you prove.
Isn't this the bank reconciliation again? The bank rec is one line of it. Cash and cards are matched against a statement item by item. For most other accounts, you show the balance is right with a document that gives the right figure, such as the lender's statement for a loan.
A template turns that comparison into the same few columns for every account. A reviewer can then read twelve accounts in the time it takes to read one. These are the columns in the template above, and why each is there:
| Column | What goes in it | Why |
|---|---|---|
| Account | The account name as it appears on the trial balance | So each line ties to one balance |
| Proved by | The document you compared it with, and who produced it | A bank statement is stronger evidence than the client's own report (which document) |
| Books | The trial balance amount at the period end | The number you're testing |
| Document | The balance on that document for the same date | The number you test it against |
| Difference | Books − document | The only amount you have to explain |
| Reconciling items | Date, description, amount, timing or error, and the fix | What explains the difference, and what still has to happen |
| Not explained | Difference − the items | The open work: the period closes when it reaches $0.00 |
| Status, preparer, reviewer | Reconciled, entry needed, or not explained; two names, and the dates prepared and reviewed | Who did it, who checked it, how soon after the period end, and what's left |
The next section walks one account through the template in six steps. Then come which document to use for each account and the worked example, which runs all twelve of one client's accounts through the template.
How do you reconcile a balance sheet account?
In short: Six steps, the same for every account. Get the two balances for one date, take the difference, and list what explains it. Then label each item, post the fixes, and have someone else sign.
The example client in this guide is Lopez Cleaning Co LLC, a fictional commercial cleaning company. Its bookkeeper, Jordan Miles, reconciles the business checking account on October 6 for the September 30 close. The steps follow the template's fields in order:
- Pick the date and the account. Put the period end in Period end (September 30, 2026). Put the account name, as it reads on the trial balance, in Account name (Business checking). Every balance that follows is at that one date.
- Enter the balance in the books. Run the trial balance at the period end on the accrual basis, so A/R and A/P agree with their agings (the accounts receivable aging report builds the A/R one). Type the account's balance in Books ($18,640.25).
- Get the document and enter its balance. Pick the bank statement in Proved by. For other accounts, pick an outside document whenever one exists. Type its balance for the same date in Document ($19,390.25). Is the document dated earlier, like a card statement that closed on the 26th? Put that date in Document date, so the workpaper shows the gap. The template takes the difference: books − document = −$750.00.
- List what explains the difference. Add a reconciling item for each cause, with its date, what it is, and its amount. The amount is positive when the item makes the books higher than the document, and negative when it makes them lower. Here that's check #1047 for −$1,425.00, the September 30 deposit for +$650.00, and the $25.00 bank fee. The template subtracts the items from the difference and shows what's not explained. The account is explained when that reaches $0.00.
- Label each item timing or error, and write the fix. Mark the check and the deposit Timing, because the October statement clears them. Mark the fee Error and write its entry in The correcting entry: debit Bank service charges $25.00, credit Business checking $25.00. The template lists every fix under Entries to post. The account counts as reconciled once the entries are posted and only timing items remain.
- Date it and have it reviewed. Enter Prepared by and Prepared on. A second person then reads the summary, checks the items marked error or over the age limit, and enters Reviewed by and Reviewed on. The template counts the days from the period end to the prepared-on date against the 30- and 45-day windows in the Texas A&M and University of Washington policies. It also warns when the preparer and reviewer are the same name, or when the review date comes before the prepared-on date.
Repeat for each account on the balance sheet, then download the workpaper. For an account that isn't a bank account, the next section says which document to use.
Which document proves each account?
In short: Use a document produced outside the client wherever one exists. A report from the client's own software only proves the ledger agrees with itself.
Auditing standards rank evidence the same way. AICPA's SAS No. 142 says "the reliability of audit evidence increases when it is obtained from external parties." It adds that "a greater susceptibility to management bias may exist when information is generated from internal sources."
You're not auditing the client, but the logic holds for a bookkeeper. A statement the bank produced can catch a mistake in the books. A report the books produced can't.
- From outside the clientA bank, card issuer, lender, payroll provider, vendor or taxing authority produced it. Examples: Bank and card statements, loan statements, payroll provider reports, vendor statements, filed returns.The strongest evidence you can get
- The client's own record, backed by outside evidenceThe client's software or staff produced it, and you test it against something outside. Examples: A/R aging checked against payments received after period end; a prepaid schedule built from the insurer's invoice.Strong once the test is done
- The client's own record aloneOnly the client's books or lists. Examples: An aging report with nothing behind it, a spreadsheet log, a balance someone typed in.Shows the ledger agrees with itself, not that it's right
The University of Washington's policy makes the point for cash. Supporting detail "would include externally prepared bank statements," while reports from its own accounting system "are generally not considered appropriate supporting detail."
Here is the document to reach for with the accounts most small businesses have. Each one is also a preset in the template, which shows what to compare it with when you open the account:
| Account | Prove it with | Usually explained by |
|---|---|---|
| Checking and savings | The bank statement's ending balance | Deposits in transit, outstanding checks, fees and interest not booked, a bank-feed transaction added twice |
| Undeposited Funds | The deposits on the next bank statement: each payment still here at the period end appears in one of its first deposits | Old payments left behind when a deposit was added instead of matched |
| Accounts receivable | The A/R aging, then large balances against payments received after the period end | Payments not applied, open credit memos, journal entries posted straight to A/R |
| Prepaid expenses | A schedule built from the invoice or policy | Monthly amortization not posted |
| Inventory | The physical count at the period end, priced at cost, on a count sheet signed by whoever counted | Items sold but not relieved from inventory, shrinkage and damage not written down, purchases received but not yet billed |
| Fixed assets (cost) | Purchase invoices, bills of sale, titles, less what was sold or scrapped | Repairs capitalized, disposals still on the books |
| Accumulated depreciation | The depreciation schedule's accumulated total at the period end. It's a credit balance, so enter both figures as positive credits. | A month's depreciation not posted, an asset sold with its accumulated depreciation left on the books, the schedule and the books using different lives |
| Credit cards | The statement balance at its closing date, plus the charges and minus the payments between that date and the period end | Charges after the statement closed, payments booked as an expense |
| Accounts payable | The A/P aging, and vendor statements for the large vendors. The accounts payable template ages the open bills on one date and shows the difference from the books. | Bills paid with an expense instead of a bill payment, duplicate bills |
| Accrued liabilities | A schedule of what was owed but not yet billed at the period end: wages earned after the last payday, interest, utilities | Last month's accrual never reversed, so this month's sits on top of it; an accrual estimated once and never updated |
| Payroll liabilities | The payroll provider's liability report and the deposits it shows; wages earned but not yet paid go through an accrued payroll entry | A tax deposit coded to expense instead of the liability |
| Sales tax payable | The tax on returns not yet paid, including the return for the period being closed (sales tax reconciliation tool) | Marketplace tax, discounts, payments coded to expense |
| Loans | The lender's statement for the same date | A payment booked all to interest, or all to principal |
| Line of credit | The balance drawn on the lender's statement at the period end, not the credit limit | A draw deposited to checking and booked as income, interest the lender charged but nobody booked, a repayment booked as an expense |
| Customer deposits | The list of deposits for work not yet done | A deposit still sitting there after the job was invoiced |
| Due to/from owner | The owner's own list of what the business owes them or they owe it, agreed with them at the period end | Personal charges on the business card posted here and never settled, a draw booked as a loan, a loan booked as a draw |
| Petty cash | The cash in the box plus the receipts not yet booked, which together equal the fund (petty cash log) | Receipts never posted, a replenishment booked to an expense |
| Opening Balance Equity | Nothing: it should be $0.00 | An opening balance never moved to owner's equity |
| Uncategorized Asset, Ask My Accountant and other holding accounts | Nothing: they hold transactions nobody has coded yet, and the period closes with them at $0.00 | Bank-feed lines added without an account, questions for the owner that were never answered |
| Retained earnings | Last year's closing figure: last year's retained earnings plus last year's net income, less distributions, from the closing balance sheet or the tax return | An entry dated in a closed year, a distribution posted here instead of to the draw or distribution account, a closed year reopened and changed |
What if you can't name any document for an account, not even a schedule you could test? In the r/Bookkeeping threads we read, an upvoted answer to "how do you reconcile balance sheet accounts?" treats that as a finding in itself. Our suggestion: write it up for the reviewer, and ask the owner what makes up the balance.
The same thread adds two quick reads: old Undeposited Funds usually means a deposit was recorded twice, and a loan balance that never moves means whole payments went to expense.
Bookkeeper tip: Some accounts have no outside document at all, like an accrual you estimated. For those, Baylor's policy allows a "reasonableness test": show how the number was built and why it makes sense. Mark it that way in the template ("Proved by: Schedule"), so the reviewer knows it's an estimate and not a match.
Worked example: a cleaning company's September close
In short: Twelve accounts at September 30, 2026: four reconcile, seven are explained but need correcting entries, and one has $750.00 nobody can explain yet.
Lopez Cleaning Co LLC is a fictional commercial cleaning company. Its bookkeeper, Jordan Miles, closes September on October 6, before sending the owner her reports. A colleague, Sam Ortiz, reviews the file on October 8. These are the numbers already loaded in the template above:
| Account | Books | Document | Difference | Result |
|---|---|---|---|---|
| Business checking | $18,640.25 | $19,390.25 (bank) | −$750.00 | Explained; $25.00 fee to book |
| Savings | $10,000.00 | $10,000.83 (bank) | −$0.83 | Explained; interest to book |
| Undeposited Funds | $1,280.00 | $0.00 (October deposits) | $1,280.00 | Explained; income counted twice |
| Accounts receivable | $9,450.00 | $9,450.00 (aging) | $0.00 | Reconciled |
| Prepaid insurance | $2,400.00 | $1,800.00 (schedule) | $600.00 | Explained; 2 months to amortize |
| Vehicles and equipment | $38,500.00 | $38,500.00 (bill of sale) | $0.00 | Reconciled |
| Credit card | $2,316.40 | $2,130.00 (statement dated Sept 26) | $186.40 | Reconciled: timing only |
| Accounts payable | $3,105.00 | $3,105.00 (vendors) | $0.00 | Reconciled |
| Payroll liabilities | $4,212.60 | $3,880.20 (provider) | $332.40 | Explained; deposit miscoded |
| Loan payable | $27,940.00 | $27,412.18 (lender) | $527.82 | Explained; payment not split |
| Customer deposits | $1,950.00 | $1,200.00 (log) | $750.00 | Not explained |
| Opening Balance Equity | $1,500.00 | $0.00 (should be) | $1,500.00 | Explained; move to equity |
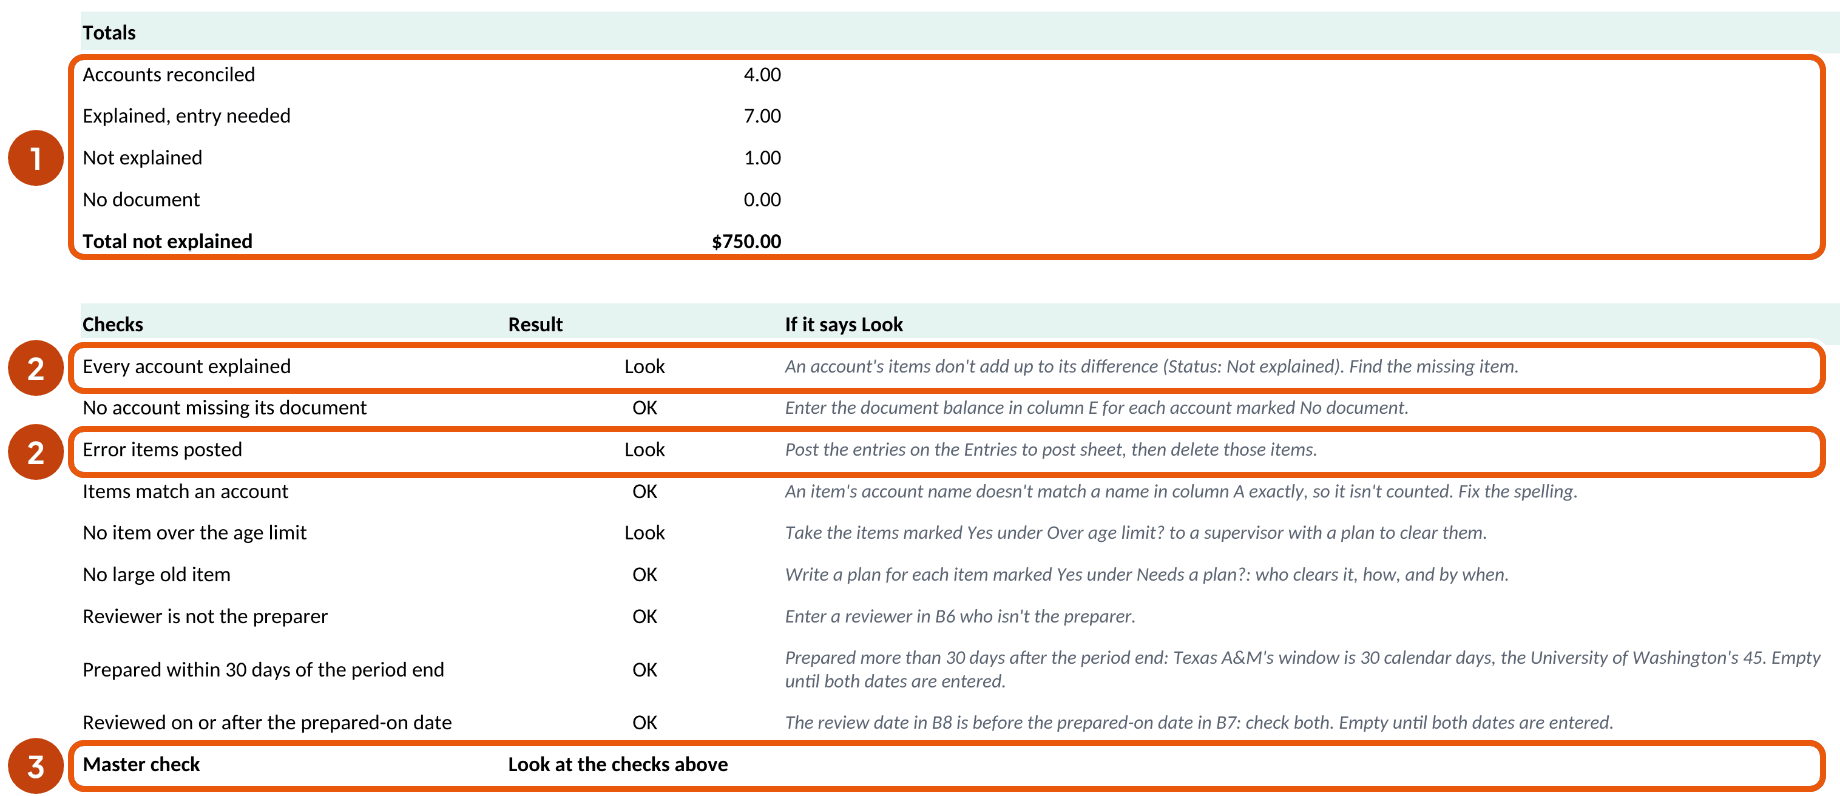
Three corrections and the open item, in detail:
Checking: two timing items and one error
| Balance in the books | $18,640.25 |
| Bank statement ending balance | $19,390.25 |
| Difference (books − bank) | −$750.00 |
| Check #1047, Sept 28, not yet paid by the bank (books lower) | −$1,425.00 |
| Sept 30 deposit, on the bank statement Oct 1 (books higher) | + $650.00 |
| Bank service fee, never recorded (books higher) | + $25.00 |
| Explained: −$1,425.00 + $650.00 + $25.00 | −$750.00 |
| Not explained | $0.00 |
Nothing is left to explain, but the account isn't finished. The $25.00 fee is an error, so it needs an entry. After it, the books show $18,615.25, which is also the bank's $19,390.25 − $1,425.00 + $650.00.
| Account | Debit | Credit |
|---|---|---|
| Bank service charges | $25.00 | |
| Business checking | $25.00 |
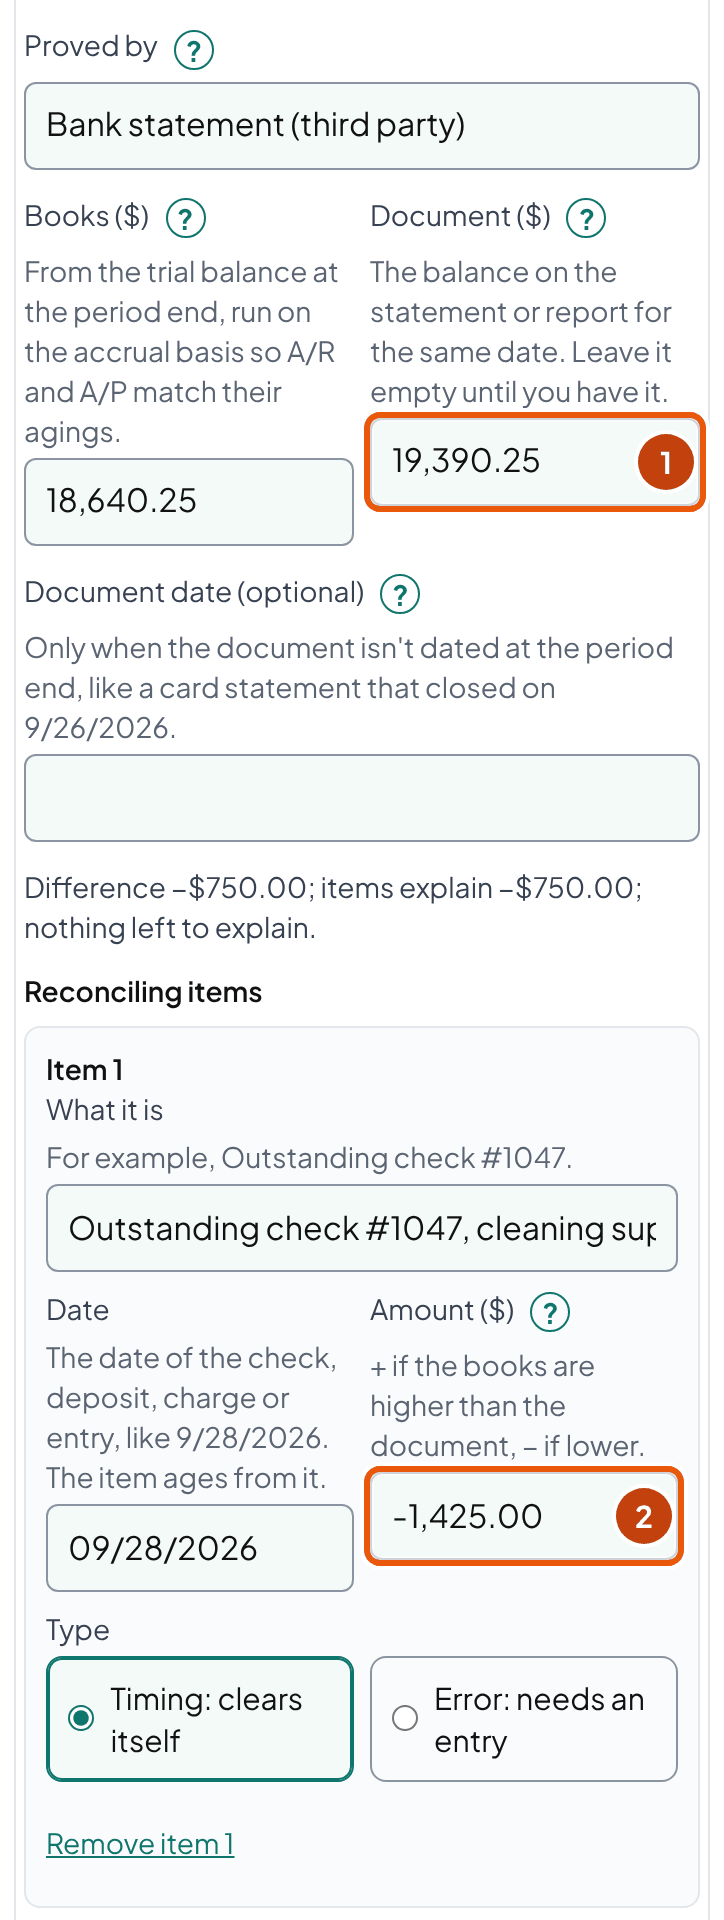
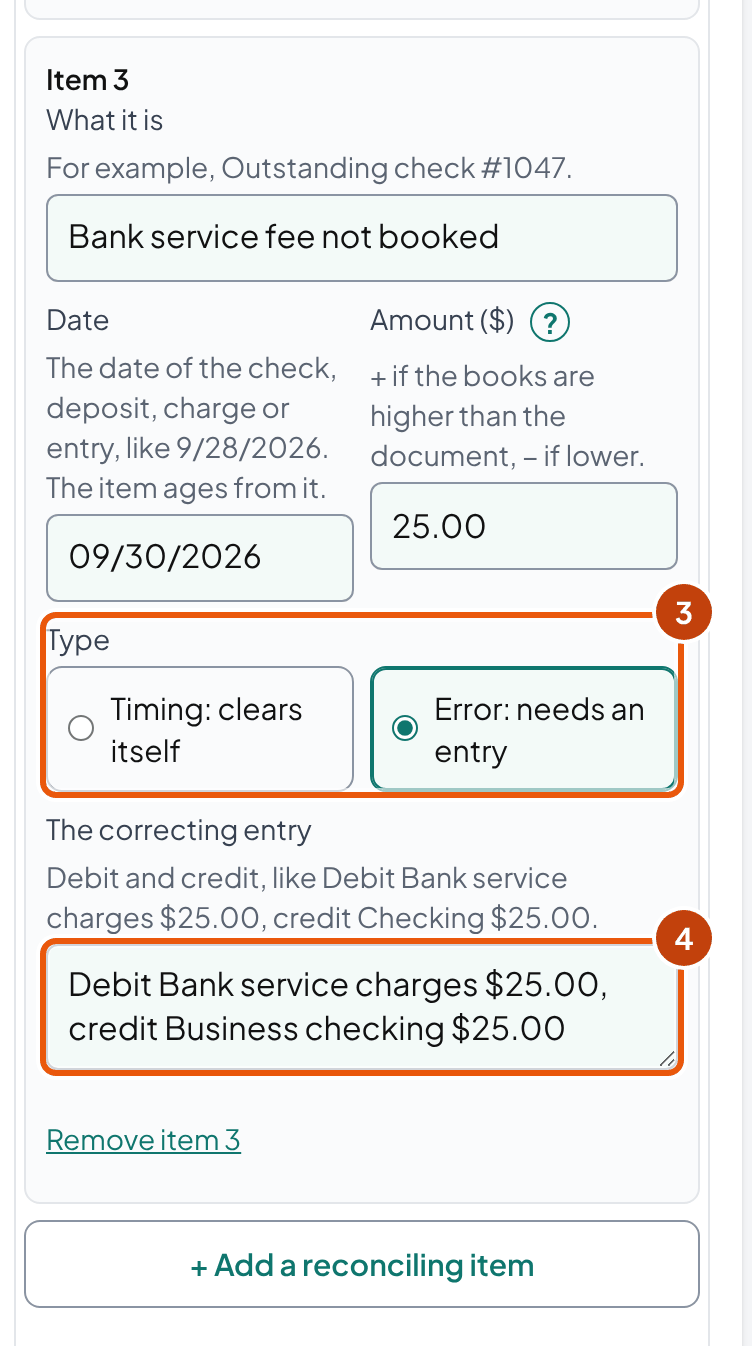
Undeposited Funds: income counted twice
Undeposited Funds holds payments received in the last few days and not yet taken to the bank. So the document that proves it is the next bank statement: each payment here at September 30 appears in one of October's first deposits. Intuit's help describes it as the account for "payments you haven't deposited at your bank."
Lopez's shows $1,280.00, made of two $640.00 customer payments: one from June 20 and one from August 12. Neither is in an October deposit, because both have been in the bank for months. So the document balance is $0.00.
How does that happen? The payment was received against the invoice, which put it in Undeposited Funds. When the deposit showed up in the bank feed, someone added it as new income instead of matching it to that payment.
The bank balance is right, but each payment now sits in Undeposited Funds for good, and the $640.00 was counted as income twice. The June payment is 102 days old, so the template flags it.
| Account | Debit | Credit |
|---|---|---|
| Cleaning revenue | $640.00 | |
| Undeposited Funds | $640.00 |
Our suggestion: in QuickBooks, it's often cleaner to delete the deposit that was added from the bank feed and match the bank line to the payment instead. The two routes correct different months. Posted in September, these two entries lower September's revenue by $1,280.00. Deleting the extra deposits lowers June's and August's by $640.00 each instead, the right months if they're still open and haven't been reported.
The loan: a payment booked all to interest
| Balance in the books | $27,940.00 |
| Lender's statement, principal at Sept 30 | $27,412.18 |
| Difference | $527.82 |
| Sept 15 payment of $689.00 booked all to interest; the lender's statement shows $527.82 of it was principal ($161.18 was interest) | $527.82 |
The principal part of the payment never reduced the loan. So the loan is overstated, and interest expense is overstated by the same $527.82.
| Account | Debit | Credit |
|---|---|---|
| Loan payable | $527.82 | |
| Interest expense | $527.82 |
Use the lender's statement for the split, not an amortization schedule you built yourself. The lender's figures include any late fees or rate changes your schedule doesn't know about.
The one that's still open
Customer deposits shows $1,950.00 in the books, $750.00 more than the client's deposit log. No item explains it yet. So the template shows it as not explained and puts $750.00 in the headline.
The usual cause is a deposit that stayed in the liability after the job was done and invoiced. So compare the deposits received in the last few months with the jobs invoiced since. Until it's found, the reconciliation isn't finished, and the reviewer sees it at the top.
A law firm's client trust liability is a deposits account with stricter rules: it's proved against a list of balances by client and against the bank. Law firm bookkeeping works one through.
Two pieces of arithmetic narrow the search. Two swapped digits always leave a difference that divides evenly by 9. Here $750.00 ÷ 9 = 83.333…, which doesn't come out even, so this isn't a transposition. An amount posted on the wrong side moves the balance by twice that amount, so also search the account for half the difference, $375.00.
The template's "For the reviewer" list does both calculations for every account that isn't explained, so the reviewer sees where to look as well as how much is open.
The other four corrections follow the same pattern:
- Savings needs $0.83 of interest income booked.
- Prepaid insurance needs two months of amortization at $300.00 each ($3,600.00 policy ÷ 12).
- A $332.40 state withholding deposit moves from Payroll tax expense back to the liability.
- $1,500.00 moves from Opening Balance Equity to owner's equity, after checking the May 31 bank statement.
All nine entries are listed in the template's "Entries to post" section and its Excel workbook.
Is an explained difference reconciled?
In short: Only when nothing is left to explain and every item left is timing. A timing item clears by itself next period, and an error stays until you post an entry. So label every item, because the label decides what happens next.
The test is one question: will this item disappear next month without anyone touching the books? An outstanding check clears when the bank pays it, so it's timing. A bank fee nobody recorded will still be missing next month and the month after, so it's an error.
Will this item disappear next month without anyone touching the books?
Yes: it's timing
- Check #1047, written Sept 28, not yet paid by the bank−$1,425.00
- Sept 30 deposit, on the bank statement Oct 1+$650.00
- Card charges Sept 27 to 30, after the statement closed+$186.40
→ No entry. Check next month that it cleared. Past 90 days, the policies we checked send it to a supervisor.
No: it's an error
- Bank service fee, never recorded$25.00
- Van payment booked all to interest: the principal part$527.82
- Two customer payments counted as income twice (2 × $640.00)$1,280.00
→ Write the correcting entry now. The account counts as reconciled once it's posted.
In the checking account above, check #1047 and the September 30 deposit are timing, and the $25.00 fee is the error. The template counts an account as reconciled only when nothing is left to explain and no error items remain. An explained error still leaves the financial statements wrong.
A few items get mislabeled often enough to call out:
| Often mislabeled | What it really is |
|---|---|
| A sale on credit listed as a "deposit in transit" | Not a bank reconciling item at all: no money moved. It belongs in accounts receivable. |
| Last month's outstanding check, still outstanding | Timing, but check it. Our suggestion: past 90 days, ask the payee, and check whether your state treats uncashed checks as unclaimed property before voiding it. |
| Interest or fees on the statement, not in the books | Errors: they need an entry, even when they're small |
| A difference you "plug" to a suspense or miscellaneous account | Not an explanation. It moves the difference somewhere a reviewer won't look. |
| A subledger that ties to the ledger | Agreement, not proof. Test large balances against something outside the books (evidence). |
Bookkeeper tip: Write the fix for every error item when you find it, in the same row. The template's "Entries to post" list and the Excel tab of the same name are built from those fixes. Posting them is then a checklist instead of a second search.
How old is too old for a reconciling item?
In short: Ninety days, in the policies we checked. Past that, an item goes to a supervisor or onto a written plan to clear it. A large one gets its plan sooner.
An item that rolls forward month after month is usually an error nobody has fixed. Published university policies put limits on it. They're a reasonable starting point for a bookkeeping practice that hasn't set its own:
| Policy | The rule |
|---|---|
| Texas A&M (revised Aug 3, 2026) | Outstanding items "resolved within 90 days of the end of the month the transaction occurred in. Any items older than 90 days should be brought to their supervisor's attention." |
| University of Washington (updated July 3, 2025) | Differences "must be cleared, corrected or written-off no later than 90 days from origination"; aging in 0-30, 30-60, 60-90 and 90+ days |
| Baylor University (Jan 2024) | Any item "exceeding $10,000 and outstanding more than 60 days" needs a resolution plan for the controller; all items "more than 90 days old, regardless of size" go on one |
These are internal policies of large institutions, not laws, and nothing requires a small business client to follow them. The template uses them as editable defaults. Change the days and the amount under "When an item is too old or too large" to your firm's own rule, and the flags and the Excel workbook follow.
In the Lopez example, two items cross 90 days: the June 20 Undeposited Funds payment (102 days) and the June 1 opening balance (121 days).
An item only ages if it keeps its original date from month to month. When September is reviewed, select Start next month from this one above the template's inputs. It moves the period end to October 31, clears the balances and the prepared and reviewed dates, and keeps each timing item with its date. It asks first whether the correcting entries were posted, then drops the error items or keeps them open. At October 31, check #1047 from September 28 is 33 days old, and anything from September still open at the December 31 close is past 90 days and gets flagged.
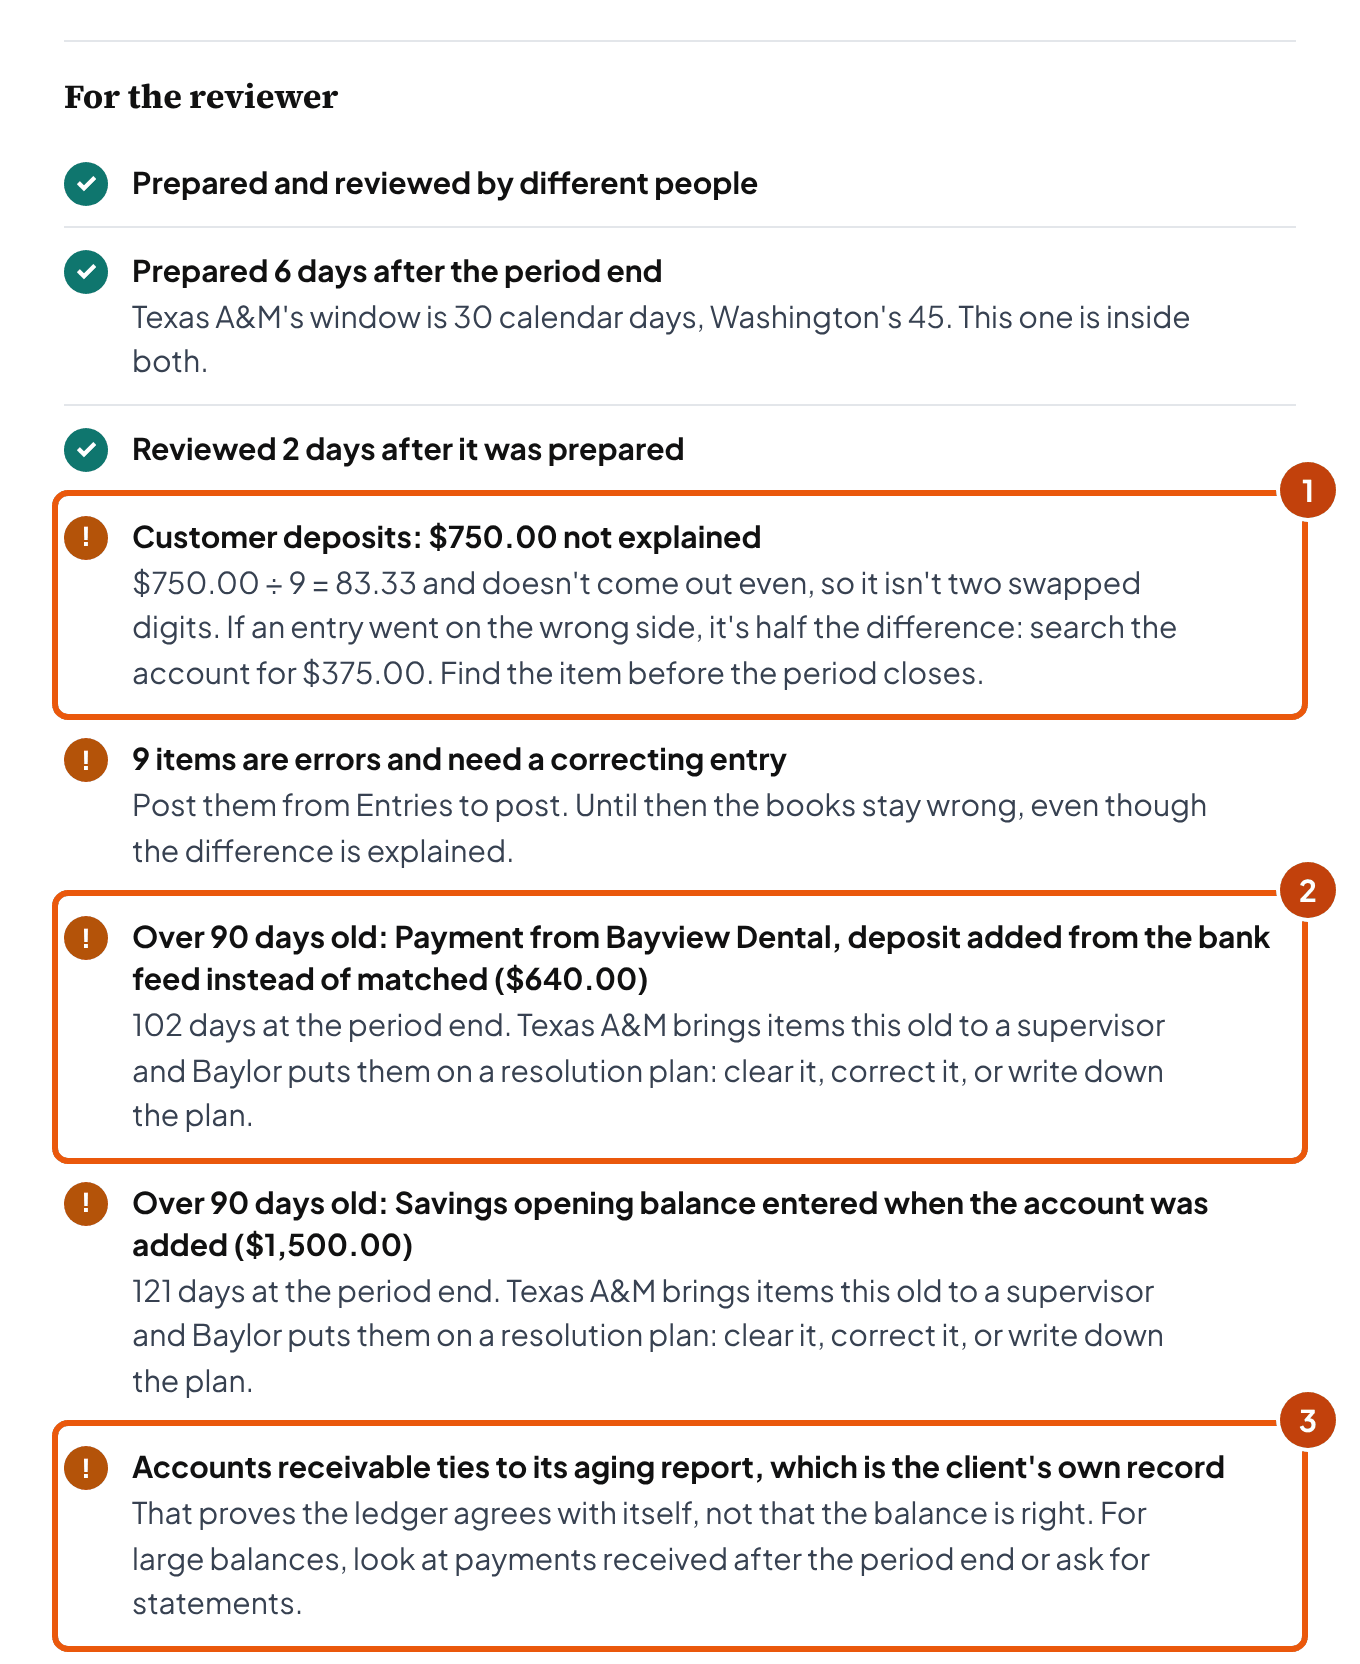
Writing off what you can't find
The University of Washington allows write-offs "only as a last resort," and any write-off over $10,000 needs approval from its Associate Vice President/Controller. A small business has fewer people, but the same caution applies.
A write-off changes the client's profit, so get the owner's agreement in writing, and record what you tried before writing it off. If the client's tax preparer would want to know about it first, keep it out of the period you're closing.
In one r/Bookkeeping thread we read, an upvoted reply says to send old balances to the owner as a list of options, because the decision is the owner's.
How do you reconcile balance sheet accounts in QuickBooks?
In short: QuickBooks reconciles bank and card accounts for you. Every other balance sheet account, and the odd balances its own features create, still need the template.
QuickBooks' Reconcile screen ties a bank or card account to its statement. Intuit's help sets the goal plainly: "the difference between the ending balances should be zero." That proves the cash account. It doesn't touch receivables, prepaid expenses, loans, payroll liabilities or equity, and it can't tell you that an amount in Undeposited Funds is months old.
A few QuickBooks features are worth knowing when you work through the rest:
- Undeposited Funds. Payments received but not yet deposited wait here. Intuit's help notes that invoice payments processed with QuickBooks Payments don't go through it. The account can also be renamed, so look for the Detail type "Undeposited Funds" when you can't find it. Anything older than a few days is the double-counting problem above.
- Opening Balance Equity. QuickBooks puts the other side of opening balances here while accounts are set up. Once setup is done, the account belongs at $0.00. Move what's left to owner's equity after checking each opening balance against its original statement.
- Closing the books. After the reconciliation is reviewed, set a closing date (QuickBooks Online: Settings, Account and settings, Advanced, Accounting), so nobody changes a period you've proved. Intuit's help says the Exceptions to Closing Date report shows "any changes made after you close your books." Run it before you start the next month.
- When last month's reconciliation stops balancing. In QuickBooks Desktop, the Reconciliation Discrepancy report (Reports, Banking) "shows any transactions that were changed since your last reconciliation." In QuickBooks Online, Intuit's advice is to check the opening and beginning balances first. It also says to review and categorize all downloaded transactions, because "you can't reconcile them until you do."
So reviewing a bank-feed line comes before reconciling it, not instead of it. Owners in the r/Bookkeeping threads we read sometimes take one for the other. Bookkeepers in other threads add that a $0.00 difference on screen isn't proof without the reconciliation report behind it.
Bookkeeper tip: Reconcile the bank first, in the client's software or with the bank reconciliation form, then copy its result into the template. The statement balance goes in as the document, and the outstanding checks and deposits in transit as timing items. The template is where every other account's reconciliation lives, side by side with cash, for the reviewer.
Which balances tie to tax forms?
In short: Payroll liabilities tie to the payroll returns, and the IRS checks them against each other. Loans and sales tax have their own documents too.
The Form 941 instructions say it directly: "The IRS matches amounts reported on your four quarterly Forms 941 with Form W-2 amounts totaled on your yearly Form W-3." If they don't agree, the client "may be contacted by the IRS or the Social Security Administration."
The amounts matched are federal income tax withheld, Social Security wages, Social Security tips, and Medicare wages and tips. When you reconcile payroll liabilities against the provider's reports every month, that year-end match holds no surprises.
| Account | Tax document | What to watch |
|---|---|---|
| Payroll liabilities | Forms 941 (quarterly) and W-3 (yearly) | The withholding and wages on the four 941s need to add up to the W-3 |
| Loans | Form 1098, box 2 (principal at January 1), for a mortgage on real property only | Only for interest of $600 or more from an individual, including a sole proprietor. The instructions say no 1098 is required if "the loan is not secured by any real property." So a van loan like Lopez's gets none, and the lender's statement is the document. |
| Sales tax payable | The state's sales tax returns | The balance left equals the tax on returns not yet paid, including the return for the period being closed (sales tax reconciliation) |
Our reading of the Form 1098 rule: the lender files it only for loans to individuals, so a corporation or partnership borrower won't get one, even for a building loan. The lender's statement is then the document for every business loan you can't tie to a 1098. For rental loans, the rental property bookkeeping template guide shows the Form 1098 box 2 check.
Keep the reconciliations with the records they support. For payroll, the IRS says to keep employment tax records "for at least 4 years after the tax becomes due or is paid, whichever is later."
How often should you reconcile balance sheet accounts?
In short: Cash every month. Everything else on a schedule set by risk, and for a small client, every month is usually simplest.
| Policy | Cash | Other accounts | Deadline |
|---|---|---|---|
| University of Washington | Monthly | At least quarterly | Within 45 days of the as-of date |
| Texas A&M | Monthly ("accounts with external statements") | Monthly for secondary systems such as QuickBooks or Excel | Within 30 calendar days of month end |
| Baylor University | Monthly | By risk: "monthly, quarterly, or annually"; payroll clearing after each payroll run | Not stated in the version we read |
Our suggestion for a small business client: reconcile every balance sheet account each month, before the reports go out. A small client's month has few enough transactions that the second account takes minutes once the first is done.
If that isn't practical, reconcile cash, cards and payroll liabilities monthly and the rest quarterly. Then reconcile every account at year end, before the tax preparer gets the books. The template's Prepared on date counts how soon after the period end the work was done, against the 30- and 45-day windows above.
Where it fits in the monthly close
One monthly close checklist shared in the r/Bookkeeping threads we read runs in this order, with a monthly cutoff for the client's documents:
- Import the month's transactions.
- Clear the uncategorized transactions.
- Reconcile the bank and card accounts.
- Check A/R and A/P.
- Send the exceptions to the client.
- Send the reports.
In our view, this template is the A/R and A/P step and every other balance sheet account: after cash and cards, before the reports go out. Clearing the uncategorized transactions first also brings the holding accounts back to $0.00, which is what their row in the template expects.
Who reviews it, and what if you work alone?
In short: Someone other than the preparer reviews and signs. If you work alone, build the second look into your calendar instead.
All three policies require it. Texas A&M is the bluntest: "The Reviewer cannot be the same person as the Preparer." The University of Washington and Baylor both require review and approval "by someone other than" the preparer. The reason is practical: the person who built a reconciliation is the one least likely to see what's missing from it.
The reviewer reads rather than redoes. Sam Ortiz reads the summary and checks that each document is for the right date and the right account. Then Sam looks at every item marked error or over the age limit, and confirms the entries were posted.
The template's "For the reviewer" list puts those things first, and it warns when the preparer and reviewer are the same name.
If you're a one-person practice
Our suggestion, not a rule from any source: review your own file on a different day from the one you prepared it. Start from the documents rather than from your worksheet.
Ask the client's owner to look at the open items and sign the summary, since they know which customer paid a deposit or which charge was personal. Write who reviewed it and when, even when the answer is "the preparer, two days later," so the file says honestly what was done.
Asking the owner about an open item
Customer deposits shows $750.00 more than your deposit log at September 30, and I can't match it to a job yet. Did a customer pay a deposit for work that's now finished and invoiced? A customer name or a rough date is enough for me to find it.
What to send the owner
Owners in the r/Bookkeeping threads we read ask how they can tell their books are actually reconciled. Bookkeepers there told them to ask for the reconciliation report for every bank and card account, dated at the last month-end, with its list of uncleared items. They also told them to ask what makes up two or three balance sheet balances.
Sending the template's summary with the monthly reports answers that before they ask.
Sending the summary with the reports
With your September reports, I've attached the reconciliation summary for September 30, 2026. Each balance sheet account is compared with its statement, report or schedule, and any open items are listed with their age. One item is still open: Customer deposits is $750.00 higher than your deposit log, and I'm tracing it now.
Why do reconciliations matter?
In short: They find errors before the owner, the lender or the tax preparer does, and sometimes they find fraud. Sarbanes-Oxley doesn't require them for a private client.
In the 2024 edition of the Association of Certified Fraud Examiners' report, built from 1,921 occupational fraud cases, 5% were first detected by account reconciliation, and tips found 43%. The 90 frauds that reconciliations caught had a median loss of $118,000. They ran a median of 9 months before they were found.
In companies with fewer than 100 employees, the median loss across all cases was $141,000. These are cases fraud examiners investigated, not a random sample of businesses. Still, the order of magnitude is the point: a small client's books have fewer people watching them.
Some pages selling reconciliation software say Sarbanes-Oxley requires reconciliations. Section 404 requires public companies to report on "the effectiveness of the internal control structure and procedures," and its text never uses the word reconciliation. The SEC's 2007 guidance lists reconciliations as one example of a control.
A private small business isn't subject to Section 404 at all. It reconciles because that's how the numbers are proved.
The template is a spreadsheet, and spreadsheets go wrong. In field audits collected by Raymond Panko, 94% of the operational spreadsheets examined had errors. So the Excel workbook keeps every input in a yellow cell and every result in a formula. A checks block with one master check says whether everything ties, and that master check shows at the top of every sheet. The Timing or Error column only takes those two words, so a typo like "Err" can't drop an error from the count.
Which mistakes make an account look reconciled when it isn't?
In short: Three that the sections above don't cover: the wrong date, the wrong order, and a period left open after it's proved.
| Mistake | Do this instead |
|---|---|
| Using a statement for a different date than the trial balance | Match the dates; for a card, adjust the statement to the period end with the charges after it closed |
| Reconciling after the reports went out | Reconcile first, then send the statements |
| Leaving the period open after it's reviewed | Set a closing date, and check the exceptions report next month |
Inherited a messy file? Where to look first
Taking over someone else's books brings a different problem: accounts marked reconciled that aren't. In the r/Bookkeeping threads we read, a CPA's list of red flags drew unanimous agreement. Most show on the balance sheet or the A/R aging:
- accounts marked reconciled that don't match the bank statement
- accounts payable with a debit balance
- credit cards with a debit balance
- Undeposited Funds that keeps growing
- sales tax payable that grows with no payments
- negative A/R balances over 90 days old
The template catches the two debit balances, and an A/R total that has gone negative. A liability with a debit balance, or an asset with a credit balance, shows in the reviewer list with its likely causes, unless the document shows the same side. A negative balance on a single customer still needs the aging report.
Other posts we read add more places to look: Opening Balance Equity with a balance, old uncleared checks, a loan missing from the balance sheet, and a petty cash account that doesn't match the box. Each account's row in the document table above says what to compare it with.
Some fixes only hide the problem. A plug to retained earnings or to a suspense account moves the difference where nobody looks. Changing an old opening balance to clear a difference rewrites a period someone already relied on. Forcing a reconciliation through in a year already filed posts the gap into that year.
A balance sheet that doesn't balance is a different problem from a bank difference. Every journal entry balances by itself, so no entry can make an unbalanced balance sheet balance. In our view, look for a software or data problem instead. Booking the difference to the P&L can't work for the same reason, though it was the most-upvoted reply in one thread we read.
Where to start? Several posters in those threads give the same order:
- Tie the opening balances to the last filed tax return or issued financial statements.
- Reconcile the bank and card accounts, month by month across all of them, so transfers between accounts match. Work forward from the earliest month, because each balance carries into the next.
- Remove duplicates, then categorize.
- Tie each balance sheet account to its document, in this template.
- Read the P&L for anything that looks wrong.
To start your own reconciliation, replace the example in the template above with your client's accounts. Or download the Excel workbook and work in that. It has spare rows for more accounts and items, and its checks tell you when everything ties.
Frequently asked questions
What is a balance sheet account reconciliation?
It proves each balance sheet account at a date by comparing its balance in the books with a document that shows the same balance from another source, such as a bank statement, a lender statement, or a vendor statement. Every difference is listed as a reconciling item, and anything not explained is investigated before the period closes.
What are the steps in a balance sheet reconciliation?
Six, for each account: fix the date and the account; enter the balance from the trial balance at that date; get the document that proves the balance, from outside the client where one exists, and enter its balance for the same date; list each reconciling item that explains the difference, with its date and amount; label each item timing or error and write the correcting entry for the errors; then post the entries and have someone other than the preparer review and sign. The template on this page has a field for each step.
What is the difference between a bank reconciliation and a balance sheet reconciliation?
A bank reconciliation proves one kind of account, cash, against the bank statement; accounting software has a reconcile screen for it, and this site has a free bank reconciliation form. A balance sheet reconciliation does the same for every account on the balance sheet: receivables, prepaid expenses, fixed assets, cards, payables, payroll and sales tax liabilities, loans, and equity, each against its own document. The bank reconciliation is one line of it.
What should a balance sheet reconciliation template include?
For each account: the balance in the books, the balance on the supporting document and where it came from, the difference, each reconciling item with its date and amount, whether the item is timing or an error, what is still not explained, and who prepared and reviewed it, with the dates. The template on this page also ages every item, flags the old and large ones, and starts next month's workpaper from this one with the timing items carried over.
How often should balance sheet accounts be reconciled?
Cash monthly, and the rest on a schedule set by risk. The university policies we checked agree on that: the University of Washington requires at least quarterly and cash monthly, Baylor sets frequency by risk, and Texas A&M wants monthly for accounts with external statements. For a small business, reconciling every account at month end before the reports go out is the simplest rule.
What is the difference between a timing difference and an error?
A timing difference clears by itself next period, like a check the bank hasn't paid yet or charges after the card statement closed. An error stays until someone posts a correcting entry, like a bank fee never recorded or a loan payment booked entirely to interest. Both explain a difference, but only an account with timing items left is truly reconciled.
How old can a reconciling item get before it's a problem?
The policies we checked use 90 days. Texas A&M says items older than 90 days go to the supervisor, and the University of Washington says differences must be cleared, corrected or written off within 90 days. Baylor also requires a written plan for any item over $10,000 that is more than 60 days old.
Does the Sarbanes-Oxley Act require account reconciliations?
Not in so many words. Section 404 requires public companies to assess their internal control over financial reporting, and the SEC lists reconciliations as one example of a control. The law applies to public companies, so a private small business client has no SOX requirement, though reconciliations are still how the books are proved.
Is a subledger report good enough to prove an account?
It proves the general ledger agrees with the subledger, not that the balance is right, because both come from the client's own software. Auditing standards treat evidence from outside parties as more reliable. For receivables and payables, back up large balances with payments received after the period end or with vendor statements.
Why should Opening Balance Equity be zero?
QuickBooks uses it to hold the other side of opening balances while accounts are being set up. Once the books are set up, each amount belongs in owner's equity or another account, so a balance left there is something to move, after checking the opening balances against the original statements.
What should be in Undeposited Funds at month end?
Only customer payments received in the last few days and not yet deposited, so each one shows up in the first deposits on the next bank statement. Intuit's help describes the account as payments you haven't deposited at your bank yet. Old amounts usually mean the bank deposit was added from the bank feed instead of matched to the payments, which also counts the income twice.
Which payroll and loan accounts tie to IRS forms?
The IRS reconciles the four quarterly Forms 941 with the year's W-2s on Form W-3: federal income tax withheld, Social Security wages and tips, and Medicare wages and tips. For a loan, Form 1098 box 2 shows principal at January 1, but only for loans to individuals secured by real property, so a business vehicle loan or a corporation's loan gets no 1098 and the lender's statement is the document to use.
How we built this page
Ledgental Team wrote this guide and built the template. Ledgental also makes a bookkeeping app that's free during its beta; this template doesn't connect to it. Everything you type stays in your browser.
What the numbers rest on
- The arithmetic is the same for every account: difference = books − document; not explained = difference − the sum of the items; an item's age = calendar days from its date to the period end. It's checked by known-answer tests worked out by hand from the Lopez example, and the Excel workbook was recalculated in LibreOffice to confirm it gives the same results as the screen.
- The age limits (90 days; over $10,000 and 60 days) come from the published policies of Texas A&M, the University of Washington and Baylor University, read on October 4, 2026. They're institutional policies, not law, so the template lets you change them.
- Every quotation (SOX §404, SEC Release 33-8810, SAS 142, the IRS form instructions, the ACFE report, Intuit's help pages) was read at the source on October 4, 2026 and is listed below.
- Reader questions come from r/Bookkeeping posts and comment threads read in October 2026. They're labeled in the text as what practitioners said, not rules.
- Not covered: consolidations and intercompany accounts, foreign currency, and how an auditor would test the accounts. Lopez Cleaning Co LLC and everyone in the example are fictional.
What changed
- October 12, 2026: the guide is rewritten in shorter sentences and paragraphs, and four headings are now questions. It adds seven accounts to the table of documents (inventory, accumulated depreciation, accrued liabilities, line of credit, due to/from owner, the holding accounts, retained earnings), two arithmetic checks for finding a difference, red flags and a starting order for an inherited file, where the reconciliation fits in the monthly close, and wording for the owner. The note on the Undeposited Funds entry now says which months each fix changes, and the unclaimed property pointer is worded as a question to check.
- October 12, 2026 (template): the reviewer list now does the ÷ 9 and half-the-difference arithmetic for any account that isn't explained, flags a liability with a debit balance or an asset with a credit balance, and checks the review date against the prepared-on date. Start next month from this one carries the timing items into the next month with their dates. In the Excel workbook the master check shows on every sheet, the Timing or Error column is a drop-down list, and a check compares the two dates. The document table can be downloaded as a CSV or printed as a checklist. The Sales tax payable row now says the balance is the tax on returns not yet paid, including the return for the period being closed. The diagram that repeated the checking account's numbers is replaced by a timing-or-error decision tree, and the summary table no longer scrolls sideways on wide screens.
- October 4, 2026: first published: the template with twelve example accounts, aging and reviewer checks, an Excel workbook with formulas and a master check, a CSV export, and this guide. Later the same day: eight more account presets, optional prepared-on, reviewed-on and document dates, and a step-by-step section.
Cite this page
Copy one of these lines to credit the page. To link to one section, use the link icon beside its heading.
- Plain line
- Ledgental, Balance Sheet Reconciliation Template, updated October 2026, https://ledgental.com/tools/balance-sheet-reconciliation-template
- APA
- Ledgental. (2026, October). Balance Sheet Reconciliation Template. https://ledgental.com/tools/balance-sheet-reconciliation-template
- Chicago
- Ledgental. “Balance Sheet Reconciliation Template.” Last modified October 2026. https://ledgental.com/tools/balance-sheet-reconciliation-template.
Reusing this page: the guide's text, tables, and screenshots are licensed under CC BY 4.0. Credit "Ledgental" with a link to this page. Quotations from the IRS and state agencies are public domain, and quotations from other sources stay under their owners' terms.
Sources
- 15 U.S.C. §7262, Management assessment of internal controls (SOX §404), Cornell LII
- Release 33-8810, Management's report on internal control over financial reporting (2007), U.S. Securities and Exchange Commission
- SAS No. 142, Audit Evidence (AU-C 500), paragraphs A6, A13, A22, A32, AICPA
- Instructions for Form 941 (Rev. March 2026), Reconciling Forms 941 with Form W-3, Internal Revenue Service
- Instructions for Form 1098 (Rev. December 2026), Internal Revenue Service
- Topic no. 305, Recordkeeping, Internal Revenue Service
- General Ledger Account Reconciliation Policy (updated July 3, 2025), University of Washington
- Monthly Financial Validation Process (January 2024), Baylor University
- SAP 21.01.01.M0.01, Reconciliation of accounts (revised August 3, 2026), Texas A&M University
- Occupational Fraud 2024: A Report to the Nations, Association of Certified Fraud Examiners
- Panko, What we don't know about spreadsheet errors today (EuSpRIG 2015), arXiv
- Deposit payments into the Undeposited Funds account, Intuit QuickBooks Online help
- Edit your closed books, Intuit QuickBooks Online help
- Fix issues when you're reconciling (QuickBooks Desktop), Intuit QuickBooks help
- Fix issues at the end of a reconciliation, Intuit QuickBooks Online help
General information, not accounting, tax or legal advice. The policies, rules and help pages quoted here were read on October 4, 2026 and can change. Lopez Cleaning Co LLC is fictional. This page isn't affiliated with the IRS, the AICPA, Intuit, or any of the universities quoted.