Key takeaways
- Every journal entry has equal debits and credits. A debit raises assets, expenses and draws. A credit raises liabilities, equity and revenue. IRS Publication 583's own example is rent: debit Rent expense $780, credit Cash $780.
- The examples below are one coffee shop's March: 22 entries from the opening balances to the month-end count. The trial balance at the end ties at $59,208.80 on both sides.
- Book card sales at the full amount, and the processor's fee as an expense. Form 1099-K reports the gross amount "without regard to" fees, so books built from net deposits come up short.
- Loan principal, credit card payments, payroll tax deposits and owner's draws aren't expenses. Each one settles a liability already recorded or moves money to the owner, so none lowers profit.
- The tool above builds any of 41 transaction types in your own amounts; the March example uses 17 of them across its 22 entries. You get the entry and why each line is there, plus what it does to the balance sheet and profit. A CSV comes in the columns of QuickBooks Online's journal import, with the customer or vendor in the Name column, and an Excel file adds a trial balance.
What is a simple journal entry?
In short: One business event, written as at least one debit and one credit for the same total. A simple entry has one of each. A compound entry has three or more lines.
Every entry answers two questions about the same amount. What did the business get? And what did it give up, or now owe? Paying rent gets the business a month in the shop, which is an expense, and gives up cash.
So you debit the expense and credit Cash, by the same amount. IRS Publication 583 uses exactly that entry as its example of a general journal:
“General Journal Date Description of Entry Debit Credit Oct. 5 Rent expense 780.00 Cash 780.00”
The same publication explains why the two sides must match. In a double-entry system "the total debits must equal the total credits after you post the journal entries to the ledger accounts. If the amounts do not balance, you have made an error and you must find and correct it."
The tool runs that check on every entry. The trial balance runs it on a whole month.
The examples on this page come from one fictional business, so they connect. Harbor Coffee Co is a coffee shop run as a single-member LLC. Its bookkeeper, Jordan Miles of Northline Bookkeeping, took over the books on March 1, 2026.
We follow March from the opening balances to the month-end count. Simple entries, like rent, sit next to compound ones, like payroll.
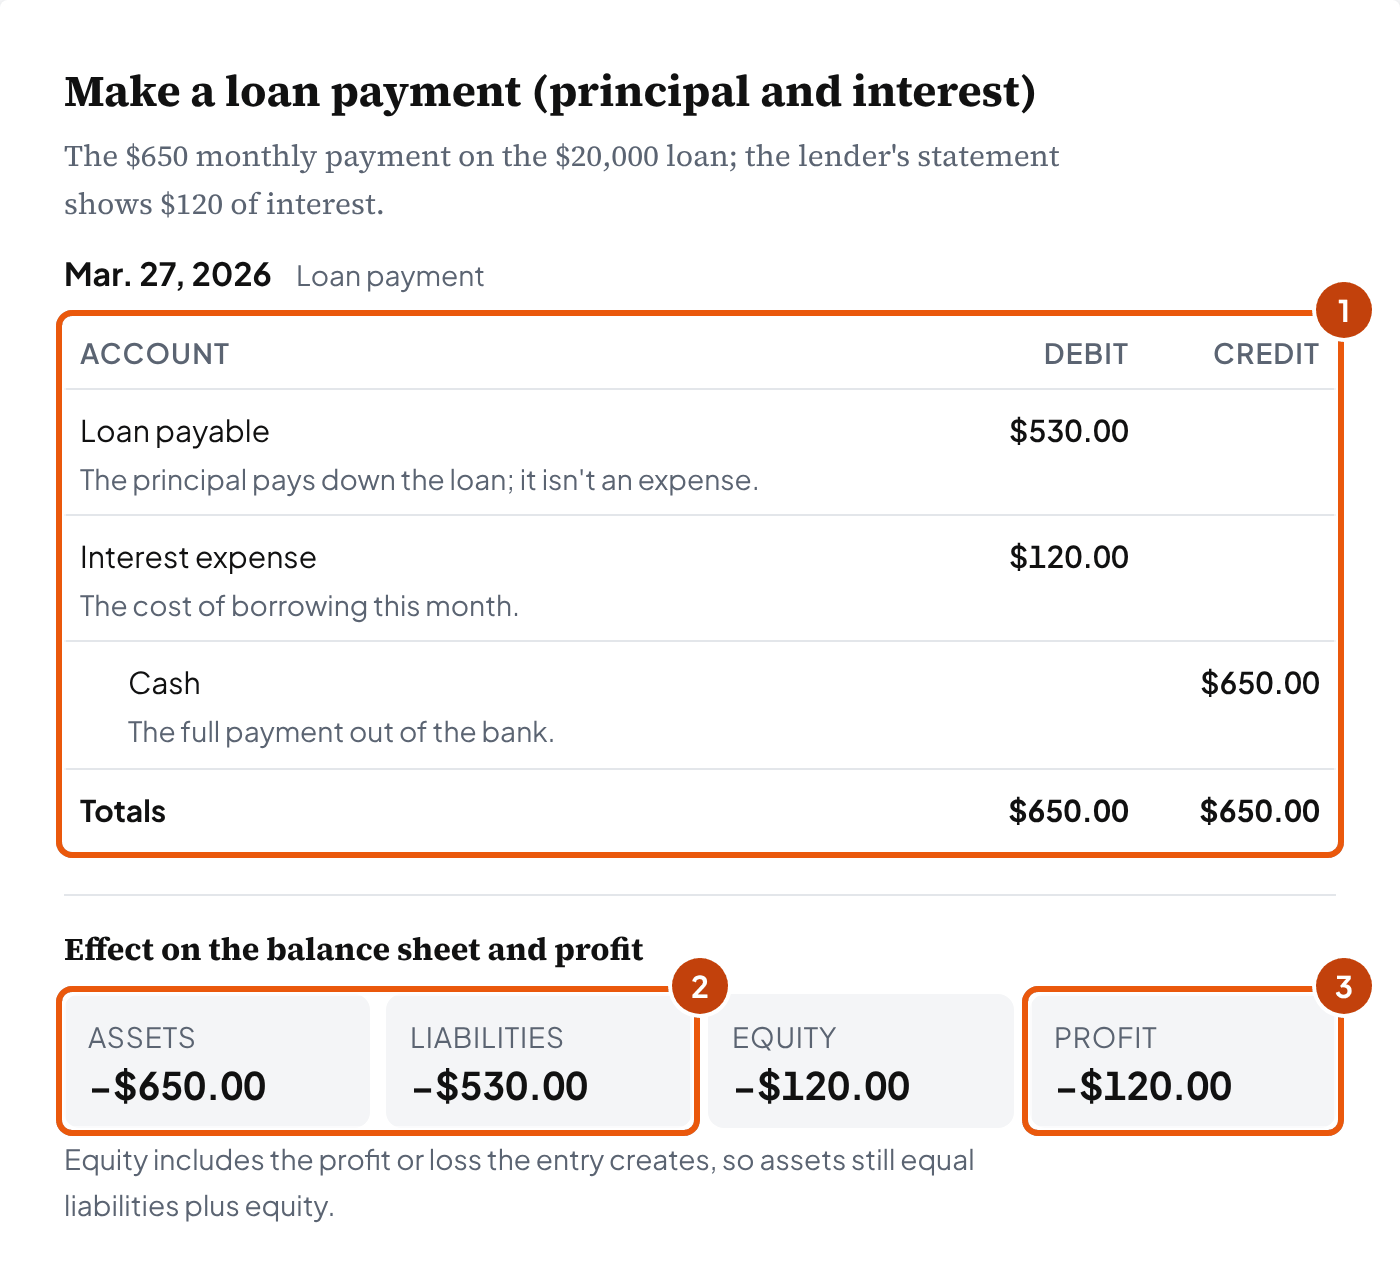
For your own amounts, pick the transaction in the tool above. It builds the entry and says why each line is there. It also shows what the entry does to assets, liabilities, equity and profit. Here is the shop's loan payment:
This guide follows US practice for a small business's books. The tax figures are 2026 federal ones (IRS Publication 15). State rules for sales tax and unemployment tax vary.
Which accounts does a debit increase, and which a credit?
In short: Debits increase assets, expenses and owner's draws. Credits increase liabilities, owner's equity and revenue. A debit decreases the accounts a credit increases, and the reverse.
| Kind of account | Examples from the coffee shop | Increased by | Decreased by |
|---|---|---|---|
| Asset | Cash, Accounts receivable, Inventory, Prepaid expenses, Equipment | Debit | Credit |
| Expense | Rent, Wages, Payroll tax, Card processing fees, Depreciation | Debit | Credit |
| Owner's draws | Owner's draws | Debit | Credit |
| Liability | Accounts payable, Credit card payable, Sales tax payable, Loan payable | Credit | Debit |
| Owner's equity | Owner's capital | Credit | Debit |
| Revenue | Sales, Catering sales | Credit | Debit |
| Contra asset | Accumulated depreciation (lowers Equipment) | Credit | Debit |
To check an entry, read each line as "up" or "down". When the shop pays its $2,000 rent, Rent expense goes up (debit) and Cash goes down (credit). When it borrows, Cash goes up (debit) and Loan payable goes up (credit).
So both sides can rise together, as long as one rise is a debit and the other a credit.
Bookkeeper tip: An entry with every line on one side can't balance, and the tool flags it. A swapped entry, with the debit and credit reversed, does balance. So check each line's direction against the table above.
Seven kinds of journal entry, one March example each
These names come up in textbooks and software menus, and every one of them is in Harbor Coffee Co's March. What makes an entry one kind rather than another is when it's posted and why, not its size:
| Kind of entry | The March entry | What makes it that kind |
|---|---|---|
| Simple | Rent, March 2: Rent expense $2,000, Cash $2,000 | One debit and one credit. |
| Compound | Payroll, March 13: six lines | Three or more lines; the debits still equal the credits. |
| Opening | Opening balances, March 1 | Posts the balance sheet a bookkeeper takes over, with capital as the balancing figure. |
| Adjusting | Depreciation, March 31 ($400) | Posted at period-end to put revenue or expense in the right month; no cash moves. |
| Reversing | The accrual reversed, April 1 | An adjusting entry with its sides swapped, dated the first day of the next period. |
| Closing | Year-end closing (example figures) | Empties revenue, expense and draws accounts into capital so the new year starts at zero. |
| Correcting | The owner's transfer, March 31 | Moves an amount from the wrong account to the right one; Cash isn't touched. |
22 journal entry examples from one coffee shop's month
In short: 22 entries take the example coffee shop's books from the February 28 balances to a March 31 trial balance that ties. They run in date order, grouped by kind. Every amount comes from the tool above, which can load the whole month into its journal.
Opening the books on March 1
A bookkeeper who takes over books mid-year starts from the last balance sheet. Jordan enters the February 28 balances as one entry. Assets go in as debits, and liabilities and accumulated depreciation as credits.
The owner's capital is the difference that makes the two sides equal, $44,000 each.
| Account | Debit | Credit |
|---|---|---|
| Cash | $18,000.00 | |
| Inventory | $2,000.00 | |
| Equipment | $24,000.00 | |
| Accumulated depreciation | $6,000.00 | |
| Credit card payable | $1,150.00 | |
| Sales tax payable | $760.00 | |
| Federal payroll taxes payable | $730.80 | |
| FUTA tax payable | $43.20 | |
| State unemployment tax payable | $194.40 | |
| Loan payable | $20,000.00 | |
| Owner's capital | $15,121.60 | |
| Totals | $44,000.00 | $44,000.00 |
The card balance, February's sales tax and February's payroll taxes are paid in March. Each payment debits the liability, not an expense.
Paying for things
Rent is the simple entry from Publication 583, paid from the bank on March 2:
| Account | Debit | Credit |
|---|---|---|
| Rent expense | $2,000.00 | |
| Cash | $2,000.00 | |
| Totals | $2,000.00 | $2,000.00 |
Insurance for a year, paid upfront on March 3, goes into the books as an asset, because the shop hasn't used the coverage yet. The month-end entry moves one month to expense: $2,400 ÷ 12 = $200 (below).
When it's deducted for tax is a separate question, with its own rules in Publication 334, so ask the preparer.
| Account | Debit | Credit |
|---|---|---|
| Prepaid expenses | $2,400.00 | |
| Cash | $2,400.00 | |
| Totals | $2,400.00 | $2,400.00 |
The roaster's bill arrives with the beans on March 6, due in 30 days. The beans go to Inventory because the shop will sell them. The month-end count turns what was used into cost of goods sold.
| Account | Debit | Credit |
|---|---|---|
| Inventory | $2,600.00 | |
| Accounts payable | $2,600.00 | |
| Totals | $2,600.00 | $2,600.00 |
The bill is still open on March 31, so Accounts payable ends the month at $2,600. The open bill also goes on the aging list, which the accounts payable template keeps and ties to this balance.
Cups and lids on the business credit card cost $310, with the sales tax the store charged. Sales tax paid on a purchase is part of what the item cost, so you don't split it out.
| Account | Debit | Credit |
|---|---|---|
| Supplies expense | $310.00 | |
| Credit card payable | $310.00 | |
| Totals | $310.00 | $310.00 |
Small cash purchases from a petty cash box post the same way, but as one entry when the box is topped up. Each slip's expense is debited, and Cash is credited for the check. The petty cash log template keeps the slips and totals them.
Paying the card statement on March 25 clears February's balance. The purchases on it were expensed when they were charged, so this entry only lowers the liability:
| Account | Debit | Credit |
|---|---|---|
| Credit card payable | $1,150.00 | |
| Cash | $1,150.00 | |
| Totals | $1,150.00 | $1,150.00 |
Sales and money coming in
Card sales arrive net of the processor's fee. Customers paid $5,184 by card from March 1 to 15: $4,800 of sales plus $384 of sales tax. The processor kept $156 and deposited $5,028 on March 16. The entry books all four amounts:
| Cash | $5,028.00 | |
| Card processing fees | $156.00 | |
| Sales | $4,800.00 | |
| Sales tax payable | $384.00 |
Debits $5,184.00 = credits $5,184.00
| Account | Debit | Credit |
|---|---|---|
| Cash | $5,028.00 | |
| Card processing fees | $156.00 | |
| Sales | $4,800.00 | |
| Sales tax payable | $384.00 | |
| Totals | $5,184.00 | $5,184.00 |
Why book the gross? The reason is on the form the processor files. The Instructions for Form 1099-K define box 1a as the total "without regard to any adjustments for credits, cash equivalents, discount amounts, fees, refunded amounts, shipping amounts, or any other amounts." The form also shows each month's gross in boxes 5a through 5l.
Harbor's card charges for March come to $10,800, while the two deposits add up to $10,476. Books built from the deposits would be $324 short of March's figure on the year's 1099-K. That's the exact amount of the fees.
A card processor sends the form "no matter how many payments you got or how much they were for," the IRS says. The over-$20,000 and over-200-transactions threshold is for payment apps and online marketplaces.
| Account | Debit | Credit |
|---|---|---|
| Cash | $5,448.00 | |
| Card processing fees | $168.00 | |
| Sales | $5,200.00 | |
| Sales tax payable | $416.00 | |
| Totals | $5,616.00 | $5,616.00 |
The second payout covers March 16 to 31. In our example the processor pays out twice a month; check the client's payout report for the actual dates and fees.
When the card payments pay open invoices instead of counter sales, the payout credits Accounts receivable rather than Sales. The payment reconciliation tool matches each payment in a payout to its invoice and drafts that entry, fee included.
An invoice for a catering order on March 10 bills an office event held that day. On the accrual method it's income once it's earned, at the event, and a receivable until it's paid.
Catering is taxable in some states. In our example it isn't taxed, so check the client's state.
| Account | Debit | Credit |
|---|---|---|
| Accounts receivable | $2,000.00 | |
| Catering sales | $2,000.00 | |
| Totals | $2,000.00 | $2,000.00 |
| Account | Debit | Credit |
|---|---|---|
| Cash | $2,000.00 | |
| Accounts receivable | $2,000.00 | |
| Totals | $2,000.00 | $2,000.00 |
The payment on March 20 only swaps one asset for another. Crediting Catering sales again would count the order twice.
Payroll and tax payments
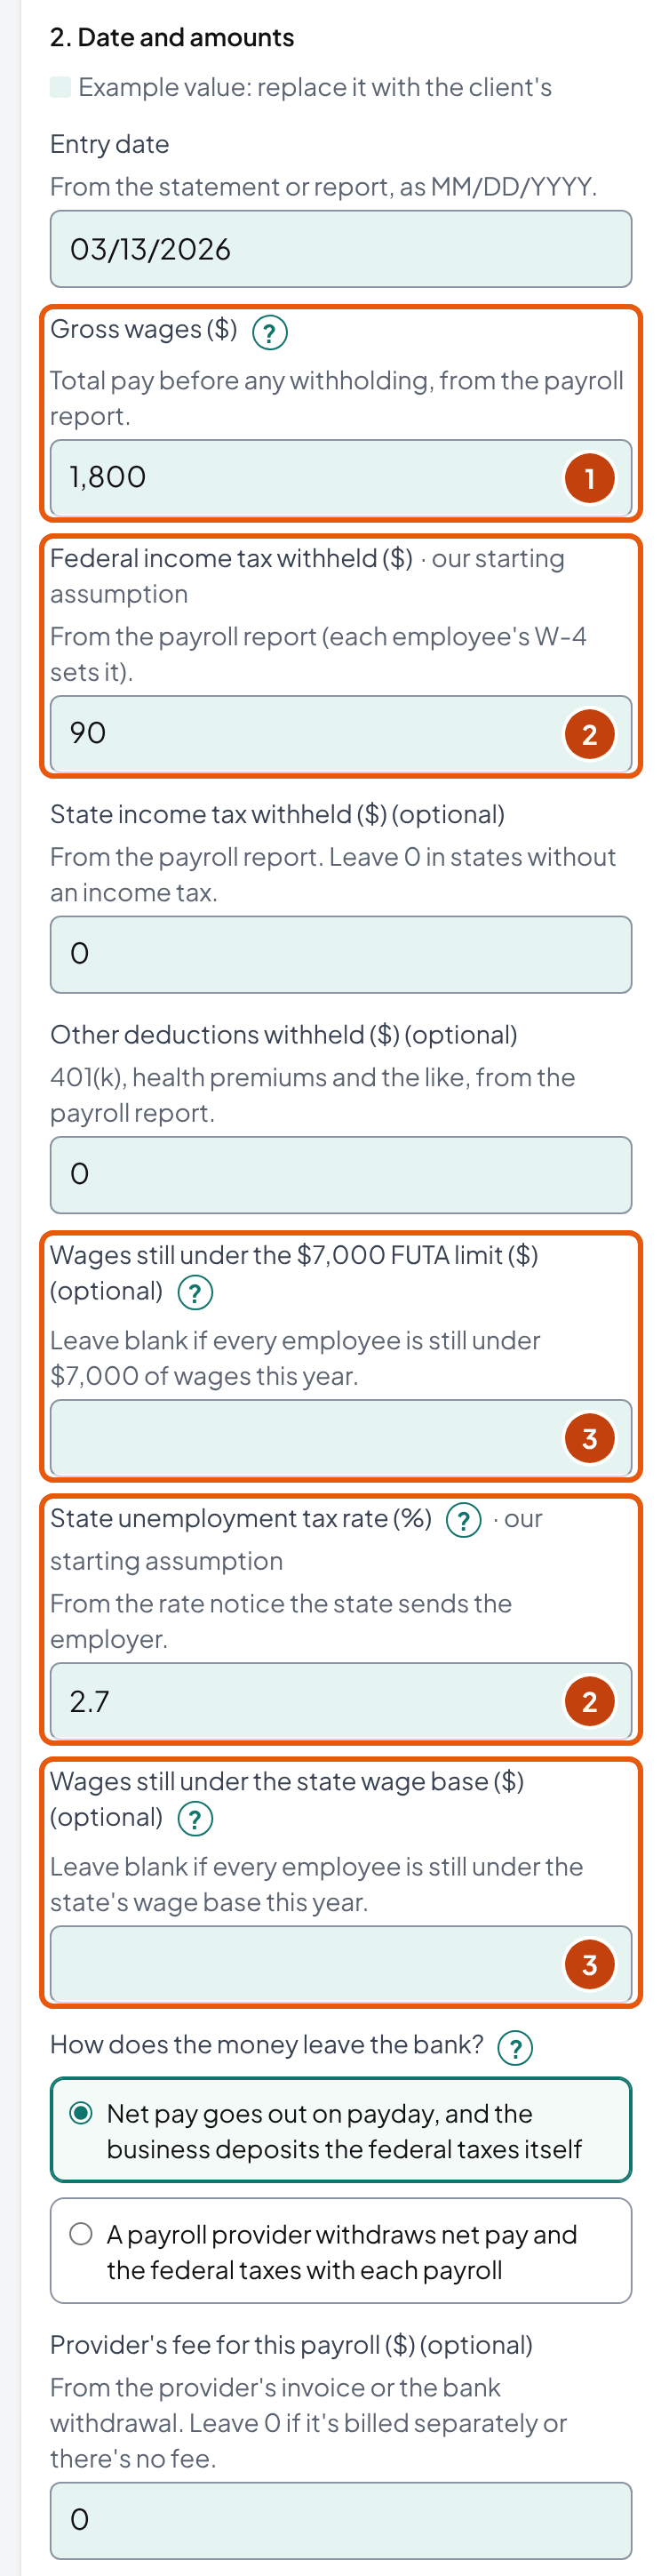
Payroll is recorded from the payroll provider's report. Two part-time baristas earn $900 each per payroll, $1,800 in all. March's paydays are Friday, March 13, because the 15th falls on a Sunday, and Tuesday, March 31.
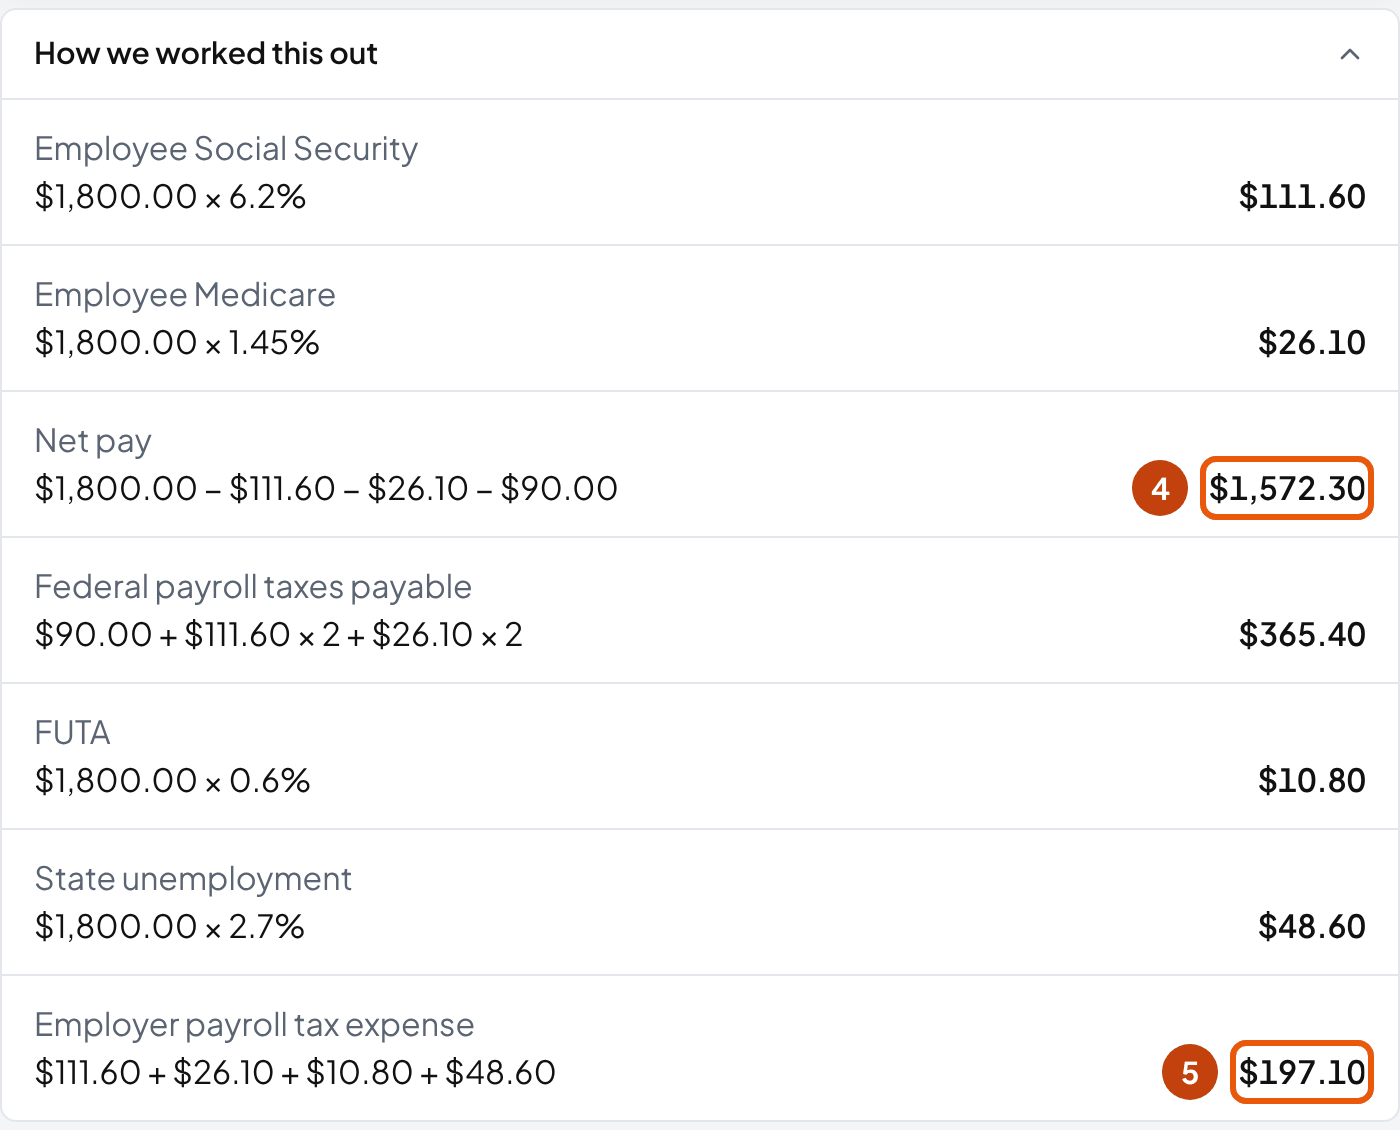
For 2026, Social Security is 6.2% for the employee and 6.2% for the employer, and Medicare is 1.45% each (IRS Publication 15). The federal income tax withheld, $90, comes from the report; it depends on each employee's W-4.
| Employee Social Security: $1,800 × 6.2% | $111.60 |
| Employee Medicare: $1,800 × 1.45% | $26.10 |
| Net pay: $1,800 − $111.60 − $26.10 − $90 withheld | $1,572.30 |
| Federal payroll taxes payable: $90 + $111.60 × 2 + $26.10 × 2 | $365.40 |
| FUTA: $1,800 × 0.6% | $10.80 |
| State unemployment: $1,800 × 2.7% (our assumption) | $48.60 |
| Employer's payroll tax expense: $111.60 + $26.10 + $10.80 + $48.60 | $197.10 |
Debits: $1,800 of wages + $197.10 of payroll tax = $1,997.10. Credits: $1,572.30 + $365.40 + $10.80 + $48.60 = $1,997.10.
| Account | Debit | Credit |
|---|---|---|
| Wages expense | $1,800.00 | |
| Payroll tax expense | $197.10 | |
| Cash | $1,572.30 | |
| Federal payroll taxes payable | $365.40 | |
| FUTA tax payable | $10.80 | |
| State unemployment tax payable | $48.60 | |
| Totals | $1,997.10 | $1,997.10 |
FUTA is 6.0% on each employee's first $7,000 of wages for the year. Publication 15 adds that "if you're entitled to the maximum 5.4% credit, the FUTA tax rate after credit is 0.6%". Each barista has earned $5,400 by March 31, so all of March's wages count.
In the payroll that takes an employee past $7,000, only the part up to $7,000 is FUTA wages, and the tool has a field for it. The 2.7% state unemployment rate is our assumption: each state sets its own rates and wage base.
Harbor's baristas have no pre-tax deductions, so their Social Security wages equal their gross pay. With health premiums through a section 125 plan, 401(k) deferrals or overtime, the payroll register template works out each tax's wages employee by employee and builds this entry from the totals row.
Additional Medicare Tax doesn't show up here. Publication 15: "Additional Medicare Tax is only imposed on the employee. There is no employer share of Additional Medicare Tax." The employer withholds it only on an employee's wages over $200,000.
The payroll tax deposit on March 13 sends February's withholding and both halves of Social Security and Medicare to the IRS. A monthly schedule depositor deposits a month's taxes "by the 15th day of the following month." The deposit only clears the liability; the expense was already recorded with each payroll.
| Account | Debit | Credit |
|---|---|---|
| Federal payroll taxes payable | $730.80 | |
| Cash | $730.80 | |
| Totals | $730.80 | $730.80 |
The sales tax return for February is paid the same day. The tax collected was never Harbor's money, so paying it isn't an expense:
| Account | Debit | Credit |
|---|---|---|
| Sales tax payable | $760.00 | |
| Cash | $760.00 | |
| Totals | $760.00 | $760.00 |
Where a state imposes the tax on the seller instead, it's part of gross receipts and deductible: see Is sales tax an expense?
The second payroll on March 31 is the same entry as the first: $1,800 of wages and $1,572.30 of net pay. We don't repeat it here; load the month into the tool to see it in the journal.
Harbor pays on the last day of the month, so nothing is owed to the baristas at March 31. When a pay period ends in one month and the paycheck lands in the next, you accrue the wages at month-end. The accrued payroll journal entry tool builds that entry and its reversal from the pay period dates.
Matching a pay run to the bank withdrawals
Does the bank feed show one payroll as two or more withdrawals? Some bookkeepers in the Reddit threads we read don't sync the payroll provider at all. They enter each pay run from the provider's report, as above, and match the withdrawals to that entry.
Match each withdrawal to the account it pays, never to an expense. The net pay withdrawal is the $1,572.30 the entry already credits to Cash. The tool's payroll entry asks how the money leaves the bank, and Harbor deposits its own taxes, as on March 13.
If the client's provider takes the federal taxes with each payroll instead, that withdrawal debits Federal payroll taxes payable. It's much larger than the $90 withheld. It also carries both halves of Social Security and Medicare: $90 + $111.60 × 2 + $26.10 × 2 = $365.40.
One way to handle several withdrawals is a payroll clearing account. Credit it for the amounts the provider will withdraw, the $1,572.30 of net pay and the $365.40 of federal taxes, instead of Cash, then debit it with each withdrawal; once every withdrawal is matched, it's back at zero. A small gap left over can be the provider's fee, which goes to its own expense account.
| Wages | $1,800.00 | |
| Payroll tax | $197.10 | |
| Payroll clearing | $1,937.70 | |
| FUTA payable | $10.80 | |
| State unemployment | $48.60 |
| Step | Debit | Credit |
|---|---|---|
| Payday entry | $1,937.70 | |
| Withdrawal: net pay | $1,572.30 | |
| Withdrawal: taxes | $365.40 | |
| Balance | $0.00 | |
A balance left over is a withdrawal not yet matched, or a fee booked here instead of to its own expense.
In the tool, choose "A payroll provider withdraws net pay and the federal taxes" under Run payroll. The payroll entry then credits Payroll clearing $1,937.70, and two withdrawal entries of $1,572.30 and $365.40 bring it back to zero. The provider's fee, if it takes one with the payroll, gets its own withdrawal entry and expense.
That choice rests on our assumption that the provider takes net pay and the federal taxes with each payroll, while the state taxes wait for their returns. It's one common setup, not every provider's. The provider's reports show what it takes and when, so match the entries to those.
Deductions such as 401(k) contributions or health premiums lower net pay too. The tool has a field for them, and they go to their own liability until they're paid over. When a deduction changes the wages a tax applies to, the payroll report's tax amounts win over the tool's.
The loan and the owner
The loan payment is $650 a month, and the lender's statement shows $120 of interest. Only the interest is a cost. The other $530 pays back money the business borrowed, and borrowing was never income either. Publication 334: "Money borrowed through a bona fide loan is not income."
| Account | Debit | Credit |
|---|---|---|
| Loan payable | $530.00 | |
| Interest expense | $120.00 | |
| Cash | $650.00 | |
| Totals | $650.00 | $650.00 |
For a rental's mortgage from a bank, interest goes on Schedule E line 12 and principal stays off Schedule E. The rental property bookkeeping template does this split for each property.
The owner's draw of $1,500 on March 28 isn't wages and isn't an expense. The Schedule C instructions say not to include "amounts paid to yourself" on the wages line.
The draw lowers the owner's equity. The owner is taxed on the shop's profit, however much she draws (how owner draws are taxed).
| Account | Debit | Credit |
|---|---|---|
| Owner's draws | $1,500.00 | |
| Cash | $1,500.00 | |
| Totals | $1,500.00 | $1,500.00 |
When the owner's money and the shop's money mix
"Is this a draw?" is one of the most repeated questions bookkeepers post. The answer depends on which way the money went and whose cost it was:
| What happened | The entry | Why |
|---|---|---|
| The owner pays a shop cost from her personal card | Debit the expense; credit Owner's capital, or a Due to owner liability if the shop will pay her back | The cost is the shop's, so it goes in the shop's expenses. Whether she's repaid is her call, so ask. |
| The shop pays her back for that cost | Debit Due to owner; credit Cash | Clears the liability. The expense was recorded when she paid. |
| She buys something personal on the business card | Debit Owner's draws; credit Credit card payable | Money taken out of the business, not a cost of running it. |
| She moves her own money into the business account | Debit Cash; credit Owner's capital | An investment, not a sale: the March 24 transfer below. |
A shop cost booked to draws drops out of the expenses, and a personal purchase booked as an expense lowers a profit the shop didn't lose. Either way, the P&L is wrong. The tool builds each row of the table in your amounts. Look for "Owner paid a business cost personally", "Pay the owner back", "Personal purchase on the business card" and "Owner puts money in".
Transfers with no receipt and no explanation are where bookkeepers disagree. In the Reddit threads we read, the most-upvoted answers say the owner decides. You ask, get the answer in writing and note it in the memo. You warn that the owner has to be able to prove a business expense in an audit, then record it as instructed.
Other posters hold the item in a draw or an "ask the owner" account until support arrives. Neither is an IRS rule. Agree one practice with the client and use it every month, so the same kind of transfer isn't booked two ways.
For the second practice, the tool's "Transfer nobody has explained yet" holds the amount in an Ask the owner account on the balance sheet. When she answers, a second entry moves it to draws or capital and the holding account is back at zero. Clear it before you close the month, or nobody can tell later whether the money was a cost, a sale or hers.
Asking the owner about a transfer: "On March 24, $1,000 moved from your personal account into the business account. Is it money you're putting into the business, a loan you want repaid, or something else? I'll record it the way you tell me. Could you reply by email, so we both have your answer in writing?"
Month-end adjustments
Adjusting entries put revenue and expenses in the month they belong to. That's why the books need them even when no cash moves. Jordan posts four on March 31.
One month of insurance is used up: $2,400 ÷ 12 months = $200. The books spread the cost over the months the policy covers, whatever the tax return does with it.
| Account | Debit | Credit |
|---|---|---|
| Insurance expense | $200.00 | |
| Prepaid expenses | $200.00 | |
| Totals | $200.00 | $200.00 |
Depreciation on the shop's $24,000 of equipment runs straight line over 5 years: $24,000 ÷ 60 months = $400 a month. Why is it an expense when no cash leaves in March? The cash left when the equipment was bought, and depreciation spreads that cost over the months the shop uses it.
The 5-year life is our assumption for the books. Tax depreciation follows IRS Publication 946 and the preparer's elections, and can be a different number. Land is never depreciated, because it "does not wear out, become obsolete, or get used up" (Publication 946).
| Account | Debit | Credit |
|---|---|---|
| Depreciation expense | $400.00 | |
| Accumulated depreciation | $400.00 | |
| Totals | $400.00 | $400.00 |
March's electricity, about $420, won't be billed until April 8. Accruing it charges it to March. The reversing entry on April 1 takes it back out, so you can enter the April bill normally without counting March's electricity a second time, in April:
| Account | Debit | Credit |
|---|---|---|
| Utilities expense | $420.00 | |
| Accrued expenses | $420.00 | |
| Totals | $420.00 | $420.00 |
| Account | Debit | Credit |
|---|---|---|
| Accrued expenses | $420.00 | |
| Utilities expense | $420.00 | |
| Totals | $420.00 | $420.00 |
A reversing entry is the original with debits and credits swapped, dated the first day of the next month. It isn't the original entry again.
At year-end the client's accountant may change an accrual you made. As an illustration with round numbers: you accrue $420, the accountant raises it to $500 with an $80 adjustment, and only your $420 reverses on January 1. The $80 then stays in Accrued expenses into the new year.
So post the accountant's change as its own entry, and reverse it with yours. Then the January 1 reversals clear both, and nothing stale is left.
Cost of goods sold comes from the count. The beans and milk on hand were $2,000 at March 1, and the shop bought $2,600. The count on March 31 came to $1,700 at cost. So $2,000 + $2,600 − $1,700 = $2,900 was used or sold.
| Account | Debit | Credit |
|---|---|---|
| Cost of goods sold | $2,900.00 | |
| Inventory | $2,900.00 | |
| Totals | $2,900.00 | $2,900.00 |
Publication 334 lets a small business taxpayer choose not to keep an inventory, but the method must still "clearly reflect income". Agree the method with the client's tax preparer.
Fixing a mistake
On March 24 the owner moved $1,000 of her own money into the business account. The bank feed rule for deposits categorized it as a sale:
| Account | Debit | Credit |
|---|---|---|
| Cash | $1,000.00 | |
| Sales | $1,000.00 | |
| Totals | $1,000.00 | $1,000.00 |
Cash is right; only the credit is wrong. The correcting entry on March 31 takes the $1,000 out of Sales and puts it in Owner's capital, without touching Cash. Left alone, the feed's entry would have added $1,000 of profit the shop never earned.
| Account | Debit | Credit |
|---|---|---|
| Sales | $1,000.00 | |
| Owner's capital | $1,000.00 | |
| Totals | $1,000.00 | $1,000.00 |
Does it balance? The coffee shop's trial balance for March
In short: Yes: after 22 entries, debits and credits both total $59,208.80. March's profit is $1,331.80, while cash rose $1,140.60.
| Account | Debit | Credit |
|---|---|---|
| Cash | $19,140.60 | |
| Inventory | $1,700.00 | |
| Prepaid expenses | $2,200.00 | |
| Equipment | $24,000.00 | |
| Accumulated depreciation | $6,400.00 | |
| Accounts payable | $2,600.00 | |
| Credit card payable | $310.00 | |
| Sales tax payable | $800.00 | |
| Federal payroll taxes payable | $730.80 | |
| FUTA tax payable | $64.80 | |
| State unemployment tax payable | $291.60 | |
| Accrued expenses | $420.00 | |
| Loan payable | $19,470.00 | |
| Owner's capital | $16,121.60 | |
| Owner's draws | $1,500.00 | |
| Sales | $10,000.00 | |
| Catering sales | $2,000.00 | |
| Cost of goods sold | $2,900.00 | |
| Rent expense | $2,000.00 | |
| Wages expense | $3,600.00 | |
| Payroll tax expense | $394.20 | |
| Card processing fees | $324.00 | |
| Supplies expense | $310.00 | |
| Insurance expense | $200.00 | |
| Utilities expense | $420.00 | |
| Interest expense | $120.00 | |
| Depreciation expense | $400.00 | |
| Totals | $59,208.80 | $59,208.80 |
A trial balance that ties proves total debits equal total credits. It doesn't prove the accounts are right: the $1,000 transfer booked as a sale balanced too.
So before you close the month, compare the bank reconciliation, the sales tax return and the payroll reports with the balances. The balance sheet reconciliation template records those comparisons account by account, with the statement or report balance next to the book balance.
The profit is $12,000 of revenue ($10,000 of sales and $2,000 of catering) less $10,668.20 of expenses. In March, profit and the rise in cash moved apart by $191.20.
A client who sees a profit figure and a smaller rise in the bank balance will ask why. The table below walks from one to the other, using only the month's entries:
| Profit for March | $1,331.80 |
| Depreciation (an expense with no cash out) | +$400.00 |
| Electricity accrued, not paid yet | +$420.00 |
| Roaster's bill, not paid yet | +$2,600.00 |
| Inventory on hand down from $2,000 to $1,700 | +$300.00 |
| More sales and payroll tax owed at month-end | +$158.80 |
| Insurance paid for the next 11 months | −$2,200.00 |
| Credit card paid down | −$840.00 |
| Loan principal repaid | −$530.00 |
| Owner's draw | −$1,500.00 |
| Owner's own money put in | +$1,000.00 |
| Change in cash ($18,000.00 to $19,140.60) | +$1,140.60 |
Use the table to explain the gap to the client. The shop made $1,331.80. The owner took $1,500 and put $1,000 back. A year of insurance went out at once, and the roaster won't be paid until April.
Which journal entries do bank feeds get wrong?
In short: The ones where the bank sees one amount and the books need two or more: net card payouts, loan payments, payroll, card payments and the owner's own money.
A bank feed records what moved through the account, and a rule assigns each amount to one account. That works for rent. It fails wherever the bank amount is a net figure, or the second half of something already recorded.
Here is each case in Harbor's March, with what the shortcut does to the numbers:
| What the feed does | The entry that's right | What the shortcut costs |
|---|---|---|
| Records the $5,028 card deposit as sales | Sales $4,800, sales tax $384, fees $156, cash $5,028 | Sales overstated by $228 (tax inside sales, fees netted out); this payout $156 short of the 1099-K's gross ($324 for the month) |
| Sends the whole $650 loan payment to an expense | Loan payable $530, interest $120 | Expenses $530 too high and the loan balance $530 too high |
| Records the $1,572.30 of net pay as wages | Wages $1,800, payroll tax $197.10, and the liabilities | Wages $227.70 short and $197.10 of employer tax missing per payroll |
| Expenses the $1,150 credit card payment | Credit card payable $1,150 | February's purchases expensed a second time |
| Books the owner's $1,000 transfer as a sale | Owner's capital $1,000 | $1,000 of profit that wasn't earned |
Fix each one with a correcting entry like the one above, or edit the feed rule so next month starts right. The tool's "Fix a wrong category" option builds the correcting entry from the amount, the wrong account and the right one.
One more feed mistake isn't a wrong account but a second entry. When the office pays the $2,000 catering invoice on March 20, the feed shows a $2,000 deposit. Categorize that deposit as Catering sales, and the order is counted twice: once with the invoice and once with the deposit. Accounts receivable never clears.
Match the deposit to the open invoice instead: Cash debited, Accounts receivable credited. A bill paid from the bank works the same way: match the payment to the open bill. The bank reconciliation still balances either way, because Cash is right. So books can look reconciled while the numbers underneath are wrong.
Bookkeeper tip: Before closing a month, compare Sales tax payable with the return, Federal payroll taxes payable with the payroll report, and the loan balance with the lender's statement. When one is off, check the difference against the amounts in this table first. A loan balance $530 too high is one payment booked as an expense. A payroll liability $365.40 short is one payroll booked from the bank.
How do closing entries work at year-end?
In short: Revenue accounts are debited and expense accounts credited to bring them to zero. The profit moves to the owner's capital, and draws are closed to capital.
Closing entries run the opposite way to each account's normal balance. Revenue built up as credits, so you debit it to empty it. Take a sole proprietor with $150,000 of revenue, $132,000 of expenses and $12,000 of draws for the year (example figures, not Harbor's):
| Account | Debit | Credit |
|---|---|---|
| Revenue accounts (each one) | $150,000.00 | |
| Income summary | $150,000.00 | |
| Totals | $150,000.00 | $150,000.00 |
| Account | Debit | Credit |
|---|---|---|
| Income summary | $132,000.00 | |
| Expense accounts (each one) | $132,000.00 | |
| Totals | $132,000.00 | $132,000.00 |
| Account | Debit | Credit |
|---|---|---|
| Income summary | $18,000.00 | |
| Owner's capital | $18,000.00 | |
| Totals | $18,000.00 | $18,000.00 |
| Account | Debit | Credit |
|---|---|---|
| Owner's capital | $12,000.00 | |
| Owner's draws | $12,000.00 | |
| Totals | $12,000.00 | $12,000.00 |
After the four entries, Income summary is back to zero. The owner's capital has gone up by $18,000 of profit and down by $12,000 of draws. So it ends the year $18,000 − $12,000 = $6,000 higher: the profit the owner left in the business.
In a partnership the profit goes to each partner's capital account under the agreement; in a corporation, to retained earnings. If the client's software rolls the year over on its own, these entries show what it did. That helps when a retained earnings or capital balance looks wrong.
Should equipment be expensed or capitalized?
In short: Capitalize it and depreciate it, unless the client elects the de minimis safe harbor and the item costs $2,500 or less per item or invoice.
Since 2016 (IRS Notice 2015-82), the de minimis threshold has been "$2500 per invoice or item for taxpayers without applicable financial statements", the IRS's tangible property page says. With one, it's $5,000 (Publication 334).
The election is made with a statement attached to a timely filed return, and the books have to expense the item too: the safe harbor applies only "to the extent such amounts are deducted by you for financial accounting purposes or in keeping your books and records" (IRS tangible property page). It "does not include amounts paid for inventory and land."
Items above the limit are capitalized in the books. Tax depreciation, including any first-year deduction, follows the preparer's elections (Publication 946).
A $2,484 grinder ($2,300 plus $184 of sales tax) fits under the limit; a $2,592 espresso machine doesn't. Both come from our sales tax article, which explains why the tax counts toward the cost. In the tool, "Buy equipment" asks whether the client uses the safe harbor and picks the account from the answer.
Journal entry examples for deposits, tips, use tax and rent in advance
In short: Eight entries readers ask about that the coffee shop's March doesn't need. Each one is in the tool above under the name in bold, with the example amounts shown here.
| What happened | The entry, with the tool's example amounts | Why it's booked that way |
|---|---|---|
| Customer pays a deposit up front: $500 down on a $2,000 catering job | When paid: debit Cash $500.00, credit Customer deposits. When the work is done: debit Customer deposits $500.00 and Accounts receivable $1,500.00, credit Catering sales $2,000.00. | Nothing is earned until the work is done, so the deposit waits in a liability. When sales tax is due on a deposit is the state's rule. |
| A day of card sales with tips: $1,200 of sales, $96 of tax, $150 of tips, $42 of fees | Debit Cash $1,404.00 and Card processing fees $42.00; credit Sales $1,200.00, Sales tax payable $96.00 and Tips payable $150.00. | Tips belong to the staff, so they never touch Sales. How payroll treats tips is outside this page; book the provider's figures. |
| Accrue use tax on a purchase: $1,000 of supplies, no tax charged | Debit Supplies expense $82.50; credit Use tax payable $82.50. | IRS Publication 334 treats tax on "the purchase or use of property as part of the cost". Texas reports use tax "in Item 3, Taxable Purchases"; 8.25% is the highest combined Texas rate, our example. |
| Rent received in advance: a landlord gets three months' rent, $4,500 | When received: debit Cash $4,500.00, credit Unearned rent. Each month: debit Unearned rent $1,500.00, credit Rental income. | The books spread it over the months. The tax return doesn't: Publication 527 counts advance rent as income in the year it's received. |
| Inventory adjustment at year-end: purchases all went to cost of goods sold; $2,000 on the books, $3,150 counted | Debit Inventory $1,150.00; credit Cost of goods sold $1,150.00. | Goods still on the shelves weren't used up, so they come back out of cost of goods sold. Agree the inventory method with the preparer (Publication 334). |
| Current portion of a loan: $6,600 of principal due next year | Debit Loan payable $6,600.00; credit Loan payable, current portion $6,600.00. | Nothing is paid and profit doesn't change. The balance sheet shows what falls due within a year. |
| Opening balances: the books you take over | Debit each asset; credit accumulated depreciation and each liability; credit Owner's capital for the difference ($15,121.60 for Harbor). | Start from the last balance sheet the accountant prepared or filed, so the books begin where the return ended. |
| Back sales tax found late: $240 of tax that went into Sales | Debit Sales $240.00; credit Sales tax payable $240.00. If it was never charged to customers, debit Sales tax expense (not collected) instead. | The tax was never income. Penalties and fines a government imposes aren't deductible (Publication 334), so they get their own account. |
A law firm's retainer starts like the customer deposit, with one more rule: the money sits in a separate trust bank account until the attorney earns it. Law firm bookkeeping has the nine entries for one month.
The owner-money entries are in the table above, and a payroll a provider runs is under matching a pay run to the bank withdrawals. Change any amount in the tool, and add the entries to your journal to see them in a trial balance.
How do you get these entries into QuickBooks Online or a spreadsheet?
In short: Type them into the journal entry screen, or import a CSV. Intuit's help page describes an import with the columns the tool's CSV uses.
Intuit's "Import journal entries" page (updated August 2026) lists the columns: Journal No., Journal Date, Account Name, Journal/Description, Debits and Credits. The path is Settings, then Import Data, then Journal Entries. Its notes matter more than the steps:
- "Turn off account numbers before you begin." You can turn them back on after the import.
- Sub-accounts need the parent: "Parent account: Sub Account". A sub-account name alone causes a "Line Account Invalid" error.
- Lines that use Accounts payable or Accounts receivable need the Name column filled in with the vendor or customer.
- New accounts must be in the chart of accounts before the import. The chart of accounts template writes them as a QuickBooks Online import file.
The tool's CSV fills the Name column on those lines from the customer or vendor name you type with the entry. Leave the name blank and the tool lists the lines that still need one before you import. The closing entries get the same warning, because their "each one" accounts stand for every revenue and expense account.
The tool also downloads an Excel file. The journal sits in yellow input cells, one row per line, and a second tab works out the trial balance from them with formulas. Its checks read 0 when every entry balances and every account is on the list; for Harbor's March the trial balance comes to $59,208.80, the same as above.
To see each account's page with a running balance, post the journal in the general ledger template. It copies every line to its account, builds the trial balance from those pages, and names the entry that breaks it.
Older answers in the QuickBooks Community, three or four years old, say the import wasn't available in the US; the current help page says it is. Import one entry into the client's file first, and check it before you import a month.
A spreadsheet is a fine journal too. IRS Topic 305 says "there's not a required method of bookkeeping you must use. However, you must use a method that clearly and accurately reflects your gross income and expenses."
Publication 583 adds that with a computerized system you must be able to produce legible records that support the entries on the return. The CSV from the tool opens in Excel or Google Sheets with one row per line.
Employment tax records are kept "for at least 4 years after the tax becomes due or is paid, whichever is later" (IRS Topic 305). Keep the payroll reports behind each payroll entry.
Common journal entry mistakes
In short: Each one puts an amount on the wrong side, books it net when the records need the gross, or books the second half of a transaction as if it were the first.
- Writing closing entries backwards. Revenue is debited to close it, and the income summary is credited.
- Calling the accrual itself a reversing entry. The reversal is the accrual with sides swapped, on the first day of the next month.
- One-sided entries. A debit with no credit can't post. If an example shows a single line, it's missing half the entry.
- Booking deposits instead of sales. Net payouts hide the fees and leave the books short of the 1099-K.
- Payroll from the bank only. Net pay isn't the wage expense, and the employer's taxes and the liabilities go missing.
- Expensing a payment of something already recorded: card statements, vendor bills, payroll tax deposits and sales tax returns.
- Categorizing a deposit the books already have. A customer's payment on an invoice is matched to the invoice, not booked as a new sale.
- Booking a customer's deposit as a sale. Nothing is earned until the work is done, so the deposit waits in a liability.
- Leaving the owner's money in sales, or a draw in wages.
Each one is a transaction type in the tool, with the entry that's right and a note on what goes wrong.
Frequently asked questions
What is a simple journal entry?
A journal entry with one debit and one credit for the same amount. Paying $2,000 of rent from the bank is one: debit Rent expense $2,000, credit Cash $2,000. IRS Publication 583 shows the same shape with $780 of rent paid on October 5. An entry with three or more lines, such as a payroll or a card payout net of fees, is called a compound entry.
What are the rules for debits and credits?
A debit increases assets, expenses and owner's draws; a credit increases liabilities, owner's equity and revenue. Each does the opposite to the other side. Every entry needs equal debits and credits, so a payment that lowers Cash (a credit) is always matched by a debit: an expense or another asset goes up, or a liability goes down.
How do you record a payment that comes in net of card processing fees?
Record the sales and sales tax at the full amount the customers paid, the processor's fee as an expense, and the deposit to Cash. For a coffee shop's March 1–15 payout in this page's example: debit Cash $5,028 and Card processing fees $156; credit Sales $4,800 and Sales tax payable $384. Form 1099-K reports the gross amount before fees, so booking only the deposit leaves the books short of the form.
What is the journal entry for a loan payment?
Split it using the lender's statement: debit Loan payable for the principal, debit Interest expense for the interest, and credit Cash for the full payment. A $650 payment with $120 of interest is a $530 debit to Loan payable and a $120 debit to Interest expense. The principal isn't an expense; it only lowers what the business owes.
How do you record payroll in a journal entry?
From the payroll report: debit Wages expense for gross pay and Payroll tax expense for the employer's taxes; credit Cash for net pay and a liability for every tax withheld or owed. For $1,800 of 2026 wages with $90 of income tax withheld, net pay is $1,572.30, the federal liability is $365.40 (withholding plus both halves of Social Security and Medicare), and the employer's taxes come to $197.10 with our 2.7% state unemployment assumption.
Is an owner's draw an expense?
No. A draw is recorded as a debit to Owner's draws, an equity account, and a credit to Cash. It doesn't lower profit, and the Schedule C instructions say not to include amounts paid to yourself in wages. The owner of a sole proprietorship or single-member LLC is taxed on the profit, whatever they draw.
How do you record a business expense the owner paid personally?
Debit the expense, because the cost is the business's whoever paid it. Credit Due to owner, a liability, if the business will pay her back, or Owner's capital if she's putting the money in. Ask the owner which and keep her answer. A $185 repair she paid on her personal card is a $185 debit to Repairs and maintenance and a $185 credit to Due to owner. When the business repays her, debit Due to owner and credit Cash.
What is the difference between an adjusting entry and a reversing entry?
An adjusting entry at month-end puts revenue or expense in the right month, such as accruing March's $420 electricity bill that arrives in April. A reversing entry is the same entry with debits and credits swapped, dated the first day of the next month, so that when the real bill is recorded as an expense in April, March's electricity isn't counted a second time.
What are closing entries and which way do they go?
At year-end, revenue accounts are debited and expense accounts credited to bring them to zero, with the other side in Income summary. Income summary is then closed to the owner's capital (credit for a profit), and draws are closed to capital (debit capital, credit draws). If the client's software rolls the year over on its own, these are the entries it makes.
How do I fix a transaction the bank feed put in the wrong account?
Edit the transaction if the period is open. If it's closed, post a correcting entry that moves the amount from the wrong account to the right one without touching Cash. When the owner's $1,000 transfer was booked as a sale, the correction is a debit to Sales and a credit to Owner's capital, both $1,000.
Can I import journal entries into QuickBooks Online from a spreadsheet?
Intuit's help page (updated August 2026) describes importing journal entries from a CSV file through Settings, Import Data, Journal Entries, with columns for journal number, date, account name, description, debits and credits, and a name for Accounts payable or receivable lines. It says to turn off account numbers first and to write sub-accounts as Parent account: Sub account. The tool's CSV uses those columns and fills Name from the customer or vendor you type. Test with one entry in the client's file before importing a month.
Does the IRS require double-entry bookkeeping?
No. IRS Topic 305 says there's no required method of bookkeeping, but the method must clearly and accurately reflect gross income and expenses. Publication 583 describes both single-entry and double-entry systems and notes that double entry is self-balancing, because total debits must equal total credits.
How we built this page
Ledgental Team built the tool and wrote this guide. Ledgental also makes a bookkeeping app that's free during its beta; this page doesn't sell it, and the tool works without an account.
What the entries rest on
- Debits and credits follow standard double-entry practice, as IRS Publication 583 describes it. The closing entries follow the textbook method in OpenStax's Principles of Accounting, section 5.1 (revenue closed to Income Summary first), which we link to rather than copy.
- Tax rules and rates were read word for word on the IRS pages listed under Sources on October 4, 2026. They cover 2026 payroll rates in Publication 15 and Form 1099-K's gross amount. They also cover Publication 334 on loans, sales tax, prepaid expenses and inventory, the Schedule C instructions on owner pay, and the de minimis safe harbor.
- The QuickBooks Online import is described from Intuit's help page as it read on October 4, 2026. We haven't run an import in a live account, so test one entry first.
- The entries added on October 12, 2026 rest on the same kind of sources. Publication 334 covers tax paid on the purchase or use of property, and government penalties. Publication 527 covers advance rent and security deposits, and the Texas Comptroller covers use tax and the 8.25% top combined rate. The IRS page on what records to keep lists what a receipt needs to show. These were read at the source in September and October 2026 and are listed under Sources.
- Practitioner practice comes from Reddit threads and posts we read in October 2026. It covers entering a pay run from the provider's report and the two ways bookkeepers handle unexplained owner transfers. It also covers tying opening balances to the last filed return, reversing only what you posted at year-end, and the bank-feed double count. It describes what posters say they do, not market data or an IRS rule.
What's our assumption
- Harbor Coffee Co, Jordan Miles and Northline Bookkeeping are fictional, and so are every balance and amount in the month.
- These are our assumptions: the 2.7% state unemployment rate, the $90 of income tax withheld, and the 5-year book life of the equipment. So are the processor's twice-monthly payouts and fees, and the year-end figures in the closing example.
- So is the payroll provider option: it assumes the provider withdraws net pay and the federal taxes with each payroll, one common setup. The amounts in the eight extra entries are examples too, and so are the customer and vendor names the tool fills in (Pier 9 Architects, Ridgeline Roasters, Linden Street Studio). Card tips are booked as owed to the staff; their payroll treatment isn't covered.
- The chart of accounts is a common small-business layout, with Due to owner, Payroll clearing and an Ask the owner holding account added. Use the client's own account names.
How the numbers are checked
One engine builds every entry in the tool and in this guide, so the two can't drift apart. 63 automated tests check that every entry balances and recompute the payroll, depreciation and inventory figures by hand. They also confirm the March trial balance ties at $59,208.80 and the profit-to-cash walk adds up to $1,140.60.
The Excel journal was recalculated in LibreOffice before release: March's trial balance came to $59,208.80, the same as the engine, and its checks read 0. A journal with one line off by $5, or an account name typed wrong, made the checks show it.
What changed
- October 12, 2026: the guide is rewritten in shorter sentences and paragraphs. New: a table for owner money mixed with the shop's, with both practices for unexplained transfers and wording to ask the owner. Also new: matching a pay run to the provider's withdrawals, reversing only what you posted at year-end, and the bank-feed double count on a paid invoice. The guide now says why depreciation is an expense with no cash out, and that the tool's CSV leaves the Name column empty.
- October 12, 2026, the tool: 12 more entries. Four cover owner money: a business cost she paid personally, paying her back, a personal purchase on the business card and a transfer nobody has explained yet. Four cover sales and tax: card tips, a customer deposit, use tax and rent received in advance. The last four are an inventory adjustment at year-end, the current portion of a loan, opening balances and back sales tax. Payroll now asks how the money leaves the bank (a provider's withdrawals go through Payroll clearing) and takes other deductions and the provider's fee. The CSV fills the Name column on Accounts receivable and Accounts payable lines and warns before an import when a name is missing. The journal downloads as Excel with a trial balance. The first payroll moved to Friday, March 13, since the 15th is a Sunday, and the closing example's draws are now $12,000, so its two last entries differ.
- October 4, 2026: first published.
Cite this page
Copy one of these lines to credit the page. To link to one section, use the link icon beside its heading.
- Plain line
- Ledgental, Journal Entry Examples, updated October 2026, https://ledgental.com/tools/journal-entry-examples
- APA
- Ledgental. (2026, October). Journal Entry Examples. https://ledgental.com/tools/journal-entry-examples
- Chicago
- Ledgental. “Journal Entry Examples.” Last modified October 2026. https://ledgental.com/tools/journal-entry-examples.
Reusing this page: the guide's text, entries, and diagrams are licensed under CC BY 4.0. Credit "Ledgental" with a link to this page. Quotations from the IRS are public domain, and quotations from Intuit stay under Intuit's terms.
Sources
- Publication 583 (12/2024), Starting a Business and Keeping Records, Internal Revenue Service
- Topic no. 305, Recordkeeping, Internal Revenue Service
- Publication 15 (2026), (Circular E), Employer's Tax Guide, Internal Revenue Service
- Instructions for Form 1099-K (12/2026), Internal Revenue Service
- Understanding your Form 1099-K, Internal Revenue Service
- Publication 334 (2025), Tax Guide for Small Business, Internal Revenue Service
- Instructions for Schedule C (Form 1040) (2025), Internal Revenue Service
- Tangible property final regulations, Internal Revenue Service
- Publication 946 (2025), How To Depreciate Property, Internal Revenue Service
- Publication 527 (2025), Residential Rental Property, Internal Revenue Service
- What kind of records should I keep, Internal Revenue Service
- Use tax, Texas Comptroller of Public Accounts
- Local sales and use tax FAQs, Texas Comptroller of Public Accounts
- Import journal entries (QuickBooks Online), Intuit
- Principles of Accounting, Volume 1, 5.1 Describe and Prepare Closing Entries for a Business, OpenStax, Rice University (CC BY-NC-SA 4.0)
General information about US bookkeeping, not tax, legal, or accounting advice. Ledgental isn't a CPA firm and isn't affiliated with the IRS or Intuit. Rules and 2026 rates were checked at the IRS in October 2026 and change every year. Harbor Coffee Co, Jordan Miles, and Northline Bookkeeping are fictional, and the amounts are examples. Check payroll and tax figures against the client's own reports and with their tax preparer.